
TAURUS
The business of reselling returned shop items
 Can I send him back, too?
IN STORES and warehouses across America, they wait: towers of toys, scarves piled on scarves, box upon box of shoes. The official start of holiday shopping in America begins on “Black Friday” on November 25th. Retailers hope to sell more than $650bn of goods this season, roughly the annual economic output of Switzerland. Ideally, companies’ supply of products would precisely match demand for them. In reality millions of items will stay on shelves or get sent back after purchase—in all of 2015 Americans returned goods worth $261bn, out of a total $3.3trn sold. What happens next?
Some returned goods will be resold by the very same retailer, but many will not. By the time an item is returned it might be either damaged or stale, points out Steven Barr of PwC, an accounting firm and consultancy; shops might want to offer newer wares. And resale is not an option for the stacks of goods that are never sold at all.
For retailers and manufacturers, this is a big headache. Dealing with unwanted goods can amount to a tenth of the cost of making and distributing them in the first place. But for…Continue reading
India grapples with the effects of withdrawing 86% of cash in circulation
 A short, sharp liquidity shock
A NEW strain of trickle-down economics has been spawned by the decision, on November 8th, to withdraw the bulk of India’s banknotes by the end of this year. As holders of now-useless 500-and 1,000-rupee ($15) notes rushed to deposit them or part-exchange them for new notes, an e-commerce site offered helpers, at 90 rupees an hour, to queue outside banks in order to save the well-off the bother.
Elsewhere, a chronic shortage of banknotes in a cash-dominated economy has left most trades depressed. Seven out of ten kiranas (family-owned grocers) have suffered a decline in business, according to a survey by Nielsen, a consultancy. Supply chains, in which wholesalers and truckers deal mostly in cash, have fractured. Some 20-40% less farm produce reached markets in the days after the reform. City folk admit to hoarding the 100-rupee note, the largest of the old notes to remain legal tender. Taxi drivers refuse to break the new 2,000-rupee note. Road-tolls have been suspended until at least November 24th, to prevent queues. Beggars have disappeared from parts of Delhi; no one has…Continue reading
The global bond-market sell-off tests Japan’s ability to keep yields down

HARUHIKO KURODA is not a man to be put off by an unexpected setback. On November 17th the governor of the Bank of Japan (BoJ) gave his defiant take on the implications for Japanese monetary policy of the global market gyrations that have followed the surprise election of Donald Trump. Interest rates, he noted, have risen in America. “But that doesn’t mean that we have to automatically allow Japanese interest rates to increase in tandem.”
A sell-off triggered by Mr Trump’s win wiped more than $1.2trn off the value of the world’s bond markets as investors bet that his administration will stoke America’s economic engines and drive up inflation. Bond yields rose sharply around the world as investors sold assets to buy dollar-denominated ones. In Japan the yen weakened and the yield on ten-year government bonds (JGBs) crept above zero for the first time in nearly two months. Since he was appointed by Shinzo Abe, the prime minister, in March 2013 as custodian of the monetary wing of “Abenomics”, Mr Kuroda has been fighting to end years of debilitating deflation. Keeping bond yields down is an important part of that…Continue reading
Economists are prone to fads, and the latest is machine learning
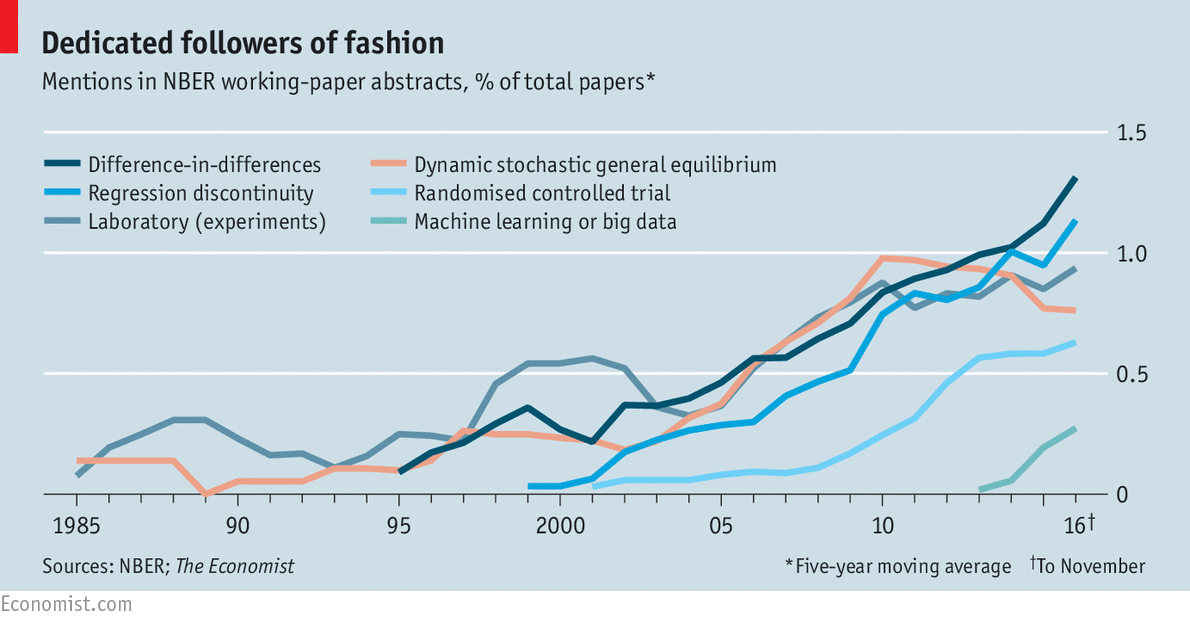
WHAT is the collective noun for a group of economists? Options include a gloom, a regression or even an assumption. In January, when PhD students jostle for jobs at the annual meeting of the American Economic Association, a “market” might seem the mot juste. Or perhaps, judging by the tendency of those writing economic papers to follow the latest fashion, a “herd” would be best. This year the hot technique is machine learning, using big data; Imran Rasul, an economics professor at University College, London, is expecting to read a pile of papers using this voguish technique.
Economists are prone to methodological crazes. Mr Rasul recalls past paper-piles using the regression-discontinuity technique, which compared similar people either side of a sharp cut-off to gauge a policy’s effect. An analysis by The Economist of the key words in working-paper abstracts published by the National Bureau of Economic Research, a think-tank (see chart), shows tides of enthusiasm for laboratory experiments, randomised control trials (RCTs) and the difference-in-differences approach (ie, comparing trends…Continue reading
Samsung is sucked into South Korea’s political crisis

IT WAS the third raid on the Samsung group in as many weeks. On November 23rd state prosecutors combed more offices of the South Korean consumer-electronics firm, part of a probe into an influence-peddling case that could be the undoing of President Park Geun-hye’s administration. The deepening inquest compounds a miserable few months for Samsung, which recently recalled 3m faulty washing machines and killed a new line of Galaxy Note phones after dozens exploded due to flawed batteries.
Last week prosecutors accused Ms Park of conspiring to coerce 50-odd companies to funnel 80bn won ($70m) to two foundations, Mir and K-Sports, controlled by Choi Soon-sil, a confidante indicted for abuse of power. The biggest grant, 20.4bn won, came from Samsung. Prosecutors suspect that it funnelled a further €2.8m ($3m) to Ms Choi through Widec Sports, a German company she used to buy horses and equestrian lessons for her daughter, a dressage athlete.
Investigators had said that the firms, including many in the pantheon of South Korean business, such as Lotte, a retail giant, and SK Group, a conglomerate, both of whose offices were raided this week,…Continue reading
A showdown looms over bank-capital rules
THEY lack the magic of “Harry Potter” and provoke even less laughter than “Police Academy”, but the sequels keep coming. In Santiago on November 28th and 29th the committee of central bankers and supervisors from nearly 30 countries that draws up global bank-capital standards is due to thrash out revisions to Basel 3, the version agreed on after the financial crisis of 2008. European (and some Asian) bankers and officials fear additional capital requirements are coming; Americans are all for the changes. Stand by for a standoff in Chile.
Spurred by Basel 3, banks have stuffed billions into capital cushions that the crisis showed to be woefully thin. Between mid-2011 and the end of last year, 91 leading lenders bolstered their common equity by €1.4trn ($1.5trn), or 65%, according to the Bank for International Settlements (BIS), which provides the Basel committee’s secretariat. The ratio of equity to risk-weighted assets, an important regulatory gauge, climbed from 7.1% to 11.8%. Although Basel 3 need not be fully honoured until 2019, most banks are far above the minimum of 4.5% (additional buffers, some at national level, raise the actual floor…Continue reading
False news items are not the only problem besetting Facebook

“MARK ZUCKERBERG, dead at 32, denies Facebook has problem with fake news.” The satirical headline, which made the rounds online this week, nicely encapsulates the most recent woes of the world’s largest social network: its algorithms, critics say, filled users’ newsfeeds with misinformation—and in the process influenced the American election result. But this is not the only problem the firm is grappling with. A volatile share price, privacy policies and advertising metrics have also kept Mr Zuckerberg (pictured) busy.
“News” that the Pope had endorsed Donald Trump or that a pizzeria in Washington, DC, is the home base of a child-abuse ring led by Hillary Clinton, were not confined to Facebook (nor were fake stories only a right-wing phenomenon). They often originate elsewhere, for instance on fake-news websites in Macedonia, which make good money via online ads, and on Twitter. But Facebook’s algorithms give prominence to such misinformation. They are tuned to maximise “engagement”, meaning they present users with the type of content that has already piqued their interest, as outrageous headlines tend to do.
Yet despite…Continue reading
The global bond-market rally tests Japan’s ability to keep yields down
HARUHIKO KURODA is not a man to be put off by an unexpected setback. On November 17th the governor of the Bank of Japan (BoJ) gave his defiant take on the implications for Japanese monetary policy of the global market gyrations that have followed the surprise election of Donald Trump. Interest rates, he noted, have risen in America. “But that doesn’t mean that we have to automatically allow Japanese interest rates to increase in tandem.”
A sell-off triggered by Mr Trump’s win wiped more than $1.2trn off the value of the world’s bond markets as investors bet that his administration will stoke America’s economic engines and drive up inflation. Bond yields rose sharply around the world as investors sold assets to buy dollar-denominated ones. In Japan the yen weakened and the yield on ten-year government bonds (JGBs) crept above zero for the first time in nearly two months. Since he was appointed by Shinzo Abe, the prime minister, in March 2013 as custodian of the monetary wing of “Abenomics”, Mr Kuroda has been fighting to end years of debilitating deflation. Keeping bond yields down is an important part of that…Continue reading
Malaysia’s central bank tries to stem a slide in the ringgit
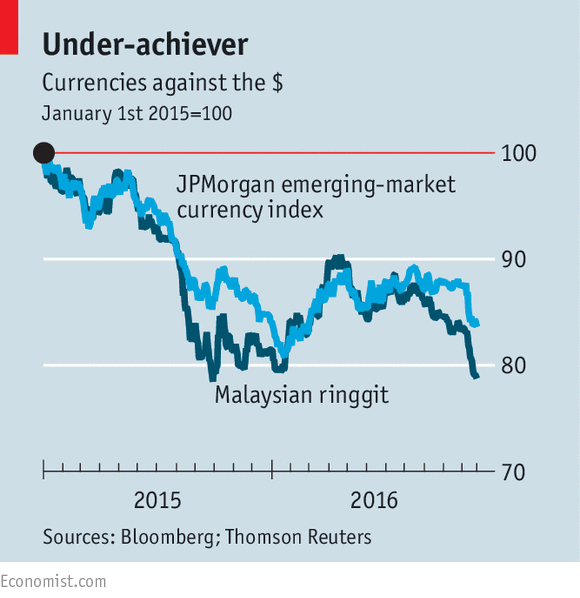
“THERE is no new policy on capital flows. There is no proxy capital control either,” insisted Muhammad Ibrahim, governor of Malaysia’s central bank, in a dinner speech on November 18th. This echoed a similar central-bank promise 15 months ago. For those hoping to bring money in and out of Malaysia, the commitments are reassuring. The frequency with which they need reiterating is less so.
It is no secret that the central bank is worried about the sharp drop in Malaysia’s exchange rate. Like other emerging-market currencies, the ringgit has suffered from China’s slowdown in the past two years and Donald Trump’s upset victory on November 8th. But, like Malaysia’s politics, beset by lurid tales of financial malfeasance, the currency has been unusually skittish (see chart).
Mr Muhammad blames what he calls “the arbitrary and unpredictable devices of the offshore markets”. Whereas China has been keen to “internationalise” the yuan, Malaysia’s central bank has an equally determined policy of “non-internationalisation”. It prohibits the trading of ringgit assets outside of its…Continue reading
British mutual-fund fees are too high

BANKS tend to grab the headlines when it comes to financial scandals and systemic risk. But many people have a lot more money squirrelled away with the asset-management industry, in the form of pensions and lifetime savings, than they do in their bank accounts. A new report* from one of Britain’s regulators, the Financial Conduct Authority (FCA), suggests that the industry is not doing a great job at looking after investors’ interests.
The British fund-management industry is huge, with some 1,840 firms managing around £6.9trn ($8.6trn) of assets. With the ten biggest fund managers representing only around 47% of the market, competition ought to be pretty intense. But the FCA report finds that fees in the actively managed sector (ie, funds that try to beat the market by picking the best stocks) have barely shifted in the past ten years. Operating margins across a sample of 16 fund-management firms have averaged 34-39% in recent years, one of the highest of any industry. Profits that heady smack more of an oligopoly than of a cut-throat battle for business.
There is one part of the market where fees have come down—passive, or tracker, funds…Continue reading