
Tag: Approved
China’s HNA Group goes on a global shopping spree
 Chen keeps spending
NOW it is a conglomerate with more than $100bn-worth of assets around the world. But HNA Group started life as a small local airline. Chen Feng, the Chinese company’s founder, led a coalition including private investors and the government of Hainan, a southern province, to launch Hainan Airlines in 1993.
Despite some help from the local government, the upstart firm was an outsider then. The central government chose three big state-run airlines to receive favoured landing slots, lavish subsidies and other advantages. The scrappy Mr Chen was undeterred. With $25m in early funding from George Soros, an American billionaire, he carved out a profitable niche.
Since then, HNA has grown quickly, mainly through acquisitions. It reported revenues of 600bn yuan ($90bn) last year. In 2016 it acquired a 25% stake in America’s Hilton Worldwide for $6.5bn and paid $10bn for the aircraft-leasing division of CIT Group, a New York-based financial firm. This week it bid nearly $1bn for Singapore’s CWT, a logistics company.
Most deals have been in industries adjacent to its core business, such as travel, tourism and logistics….Continue reading
Google is accused of underpaying women

GOOGLE has made a fortune by helping people dig up whatever information they seek. But in a court hearing on April 7th, America’s Department of Labour (DoL) accused the company behind the profitable search engine of burying the fact that it pays its female employees less than their male counterparts. The accusation of lower compensation for women forms part of a lawsuit by the DoL, which has asked Google to turn over detailed information on pay. The department has not released data to back its assertion, and Google denies the allegation.
Whatever the outcome in court, the government’s recriminations risk marring Google’s image. Just three days earlier it had taken to Twitter to boast that it had “closed the gender pay gap globally”. That claim is now under suspicion. It is true that at Google’s parent company, Alphabet, several women hold high positions, including Ruth Porat, the chief financial officer, and Susan Wojcicki, who runs YouTube, an online-video business. But the important question is not only whether a few women get promoted but also how those in the middle and lower ranks fare.
What figures there are paint a depressing picture about the…Continue reading
Cloudification will mean upheaval in telecoms

IN THE computing clouds, startups can set up new servers or acquire data storage with only a credit card and a few clicks of a mouse. Now imagine a world in which they could as quickly weave their own wireless network, perhaps to give users of a fleet of self-driving cars more bandwidth or to connect wireless sensors.
As improbable as it sounds, this is the logical endpoint of a development that is picking up speed in the telecoms world. Networks are becoming as flexible as computing clouds: they are being turned into software and can be dialled up and down as needed. Such “cloudification”, as it is known, will probably create as much upheaval in the telecoms industry as it has done in information technology (IT).
IT and telecoms differ in important respects. One is largely unregulated, the other overseen closely by government. Computing capacity is theoretically unlimited, unlike radio spectrum, which is hard to use efficiently. And telecoms networks are more deeply linked to the physical world. “You cannot turn radio towers into software,” says Bengt Nordstrom of Northstream, a consultancy.
The data centres of big cloud-computing providers are packed…Continue reading
Why carmakers need to get bigger

CARS are getting bigger. Motorists worldwide have for years been abandoning four-door saloons in favour of bulkier SUVs. Carmakers have become bigger, too. Four car firms now make around 10m vehicles a year in order to reap economies of scale, particularly in the mass-market bit of the business where profit margins can be painfully thin.
Many executives also believe that size is the only protection against the technological upheaval sweeping the industry. But bulking up fast is easier said than done. Lots of different constituents have to be won over. And most car bosses are still reticent about taking the plunge on mergers because many have been catastrophes. Daimler’s acquisition of Chrysler in 1998, for example, was a notable disaster. The list of past crashes is lengthy. Indeed, one recent deal—General Motors’ sale of Opel, its European arm, to France’s PSA Group for €1.3bn ($1.4bn)—seems to go directly against the imperative to bulk up.
In fact, that deal has had the effect of spurring more talk of consolidation. Speculation centred at first on a possible mega-merger between GM and Fiat Chrysler Automobiles (FCA), itself the result of a deal in 2014 (FCA’s…Continue reading
The University of Chicago worries about a lack of competition

ONE sign that monopolies are a problem in America is that the University of Chicago has just held a summit on the threat that they may pose to the world’s biggest economy. Until recently, convening a conference supporting antitrust concerns in the Windy City was like holding a symposium on sobriety in New Orleans. In the 1970s economists from the “Chicago school” argued that big firms were not a threat to growth and prosperity. Their views went mainstream, which led courts and regulators to adopt a relaxed attitude towards antitrust laws for decades.
But the mood is changing. There is an emerging consensus among economists that competition in the economy has weakened significantly. That is bad news: it means that incumbent firms may not need to innovate as much, and that inequality may increase if companies can hoard profits and spend less on investment and wages. It may yet be premature to talk about a new Chicago school, but investors and bosses should pay attention to the intellectual shift, which may change American business.
The fear that big firms might come to dominate the economy and political life has its roots in the era of the robber barons of the…Continue reading
Rescuing Myanmar’s farmers from the debt trap
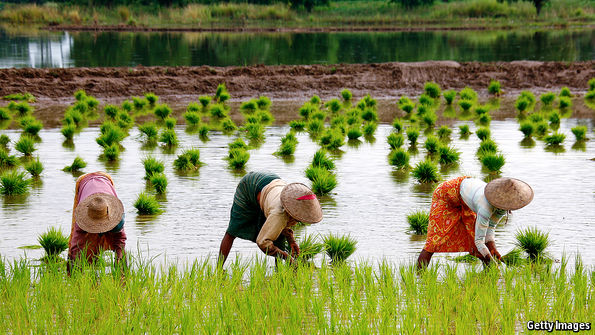 Living on borrowed rice
WHEN Myo Than was a young man, his family had 12 hectares of farmland in Dala, a rural township just across the river from Yangon, Myanmar’s biggest city. His mother sold most of it after his father died. Mr Myo Than grows rice on what’s left, but water shortages mean he reaps just one harvest each year. He borrows money from the Myanmar Agricultural Development Bank (MADB)—1.5m kyats ($1,100) this year, at an annual rate of 8%—to cover planting costs. But rice is a low-return crop. To repay the bank he borrows from local moneylenders at a rate of around 4% each month. Mr Myo Than owes them $7,300. He has given his land deeds to a moneylender as security.
Mr Myo Than’s predicament is not unusual: poor crop returns and usurious loan terms have kept Myanmar’s farmers trapped in poverty and debt. Around 60% of Myanmar’s population are engaged in agriculture. Most are poor, and farm small plots of land using age-old manual techniques. Farmers scythe rice fields; water buffaloes pull wooden ploughs; hay-laden bullock-carts trundle down narrow roads.
Many farmers borrow to cover planting costs, buy equipment…Continue reading
The EFTA countries show how hard Brexit will be for Britain

NORWAY offers much to envy. The food is tasty, public services are great and the people are impossibly good-looking. Its trade policy looks equally desirable. Though it trades heavily with the EU, Norway can also strike trade deals all over the world, either operating in concert with the three other members of the European Free Trade Association (Iceland, Liechtenstein and Switzerland) or on its own. Members of EFTA have dozens of deals, including two with China, with which the EU cannot even start negotiations.
After it leaves the EU, Britain will look much like an EFTA country: a rich economy with close links to Europe, but also seeking trade deals elsewhere. It is superficially an attractive prospect. Yet EFTA’s half-in-half-out relationship with the EU hinders its trade as much as it helps.
EFTA’s flexibility in trade stems from its odd relationship with the EU. Switzerland has a series of bilateral agreements, whereas Norway, Iceland and Liechtenstein are part of the single market through the European Economic Area (though with opt-outs for agriculture and fisheries). Crucially, however, all are outside the EU’s customs union, an agreement which regulates…Continue reading
A different approach to mobile money in Africa
WITH her phone in one hand and a live chicken in the other, Brenda Deeomba comes for her money. Her husband is a builder in Lusaka, the Zambian capital, and sends his wages home through Zoona, a money-transfer company. She receives them at a roadside booth in Chongwe, a nearby town, using a PIN number sent to her phone. It is a safe way to get the money, says Ms Deeomba, above muffled squawks.
Money-transfer businesses are proliferating in Africa. But Zoona is unusual. Unlike M-PESA, the best-known, in Kenya, it is not run by a phone company. Nor is it owned by a bank. Instead, Zoona has built a business from scratch. It processed $200m in transactions last year and bubbles with ambition: Mike Quinn, its (Canadian) chief executive, talks of reaching 1bn customers.
Zoona was founded in Zambia in 2009 by two brothers, Brad and Brett Magrath. As a startup, they were at a disadvantage, having to recruit their own agents. Zoona did so by seeing them as its core customers, giving them credit and training to set up their own franchises. Some are impressively successful. In central Lusaka, Misozi Mkandawire presides over an empire of kiosks. She started with Zoona while at college. Her profits can now reach 50,000 kwacha ($5,200) a month. That is exceptional. Last year the average agent made $548 in monthly commission, before costs. Globally, nearly half of…Continue reading
The boss of scandal-plagued Barclays gets into trouble himself

IN HIS first 17 months running Barclays, Jes Staley seemed scarcely to put a foot wrong. The American has narrowed the British lender’s ambitions, to focus on retail business at home, corporate and investment banking on both sides of the Atlantic, and credit cards. He is pulling Barclays out of Africa, after a century, and has sped up its retreat from other markets. He has also poached several folk from JPMorgan Chase, where he spent 34 years and ran the investment bank.
On April 10th it emerged that Mr Staley had clumsily planted a boot out of bounds. Last June Barclays’ board and an executive received anonymous letters about a “senior employee” hired earlier in 2016. These, say the bank, raised concerns “of a personal nature” about this person and Mr Staley’s role in dealing with the matter “at a previous employer” (presumably JPMorgan Chase).
Mr Staley, seeing the letters as “an unfair personal attack” on the newcomer, asked Barclays’ security team to find out who had written them, but was told that this should not be done. In July he inquired whether the matter was resolved—and formed the “honestly held, but mistaken” belief…Continue reading
A new mood of optimism infects investors in China’s banks
GUO SHUQING, China’s new banking regulator, knows the enormity of his task. China’s banking system, he observed last month, is worth more than $33trn. So it is bigger than any other country’s, and even than Europe’s as a whole. And he is well aware of the pitfalls left by a decade of breakneck lending growth. But if Mr Guo is nervous, he is hiding it. “All problems and contradictions will be resolved,” he says.
Of course, a Chinese official can be expected to express confidence about Chinese banks. More surprising is that a small but growing number of analysts and investors seem to concur. Chinese bank shares are up by a quarter since early last year. One investment bank, Morgan Stanley, has declared that China’s lenders are “in a sweet spot”. Another, Goldman Sachs, has upgraded China to “overweight”—that is, recommending that clients buy Chinese shares—and is especially positive about the banks. Shanghai Financial News, a local newspaper, described the new mood around these giant institutions as the “return of the king”. The question is whether it will be a long, stable reign or a short-lived, turbulent one.
The…Continue reading