
Tag: FINANCE
Digitisation shakes up corporate-bond markets

JUST a few decades ago, an asset manager wanting to trade shares, bonds or derivatives almost always had to call up the trading desk at a big investment bank. Today shares and many derivatives can be traded with a few simple clicks (or even in fully automated fashion, using algorithms). But buying and selling bonds, especially corporate bonds, is still an old-fashioned business. Over four-fifths of trading in American corporate bonds still takes place with a dealer, usually over the phone. Yet digitisation is at last beginning to change the structure of bond markets: witness the announcement on April 11th by Tradeweb, an electronic-trading platform, that it is to offer “all-to-all” trading in European corporate bonds, ie, a system in which any market participant can trade with any other.
Electronic bond-trading is not in itself new. Tradeweb’s platform, initially limited to trading of American Treasuries, was unveiled in 1998. Around half of Treasuries, and nearly 60% of European government bonds, are now traded electronically, reckons Greenwich Associates, a consultancy. But for corporate bonds, progress has been slower: only 25% of global trading volume in…Continue reading
America’s big banks have an encouraging first quarter

WHAT a difference a year makes. When America’s big banks reported first-quarter earnings for 2016, the mood was glum. The Federal Reserve was proving tardier than hoped in raising interest rates, which held down lending margins. Jitters about the world economy meant rotten results for investment-banking units, in what is usually their best season of the year. Regulators added to the misery: last April the Fed rejected the “living wills”—plans for liquidating lenders that get into trouble—of five of the six largest banks.
This spring bankers are happier. Business perked up last year after that dismal start. Donald Trump’s election in November, accompanied by promises to ginger up the American economy, cut corporate taxes and roll back regulation of finance, gave banks’ shares a lift (see chart). The Fed raised rates in December and again in March and is likely to keep increasing them. And 2017’s first-quarter results have, mostly, seen an improvement—though the cheer was not evenly shared.
“Wall Street activities have performed better than Main Street ones,” says Mike Mayo, an independent bank analyst. Revenues from capital-market…Continue reading
A trade economist wins the John Bates Clark medal

IN 1853 the government of India, then directed by Britain’s East India Company, began construction of a vast rail network, continued by the British Raj, established in 1858. At the time, most inland transport in India was hauled by draught animals: with carts where roads existed and were passable; packed on animals’ backs when they were not, which was often. Moving goods across the great expanse of the subcontinent was costly and painfully slow. That changed with the arrival of the railway. Between 1853 and 1930 more than 67,000km (42,000 miles) of rail was laid across India, providing transport that was fast, cheap and reliable. A bullock could carry a pack 30km a day; an engine could haul freight 600km over the rails in the same time.
Working out the impact of this took Dave Donaldson (a PhD candidate at the London School of Economics when he started trying) nearly a decade. He dug through mountains of yellowed colonial-era records that had never before been collated and digitised. He found that eight different kinds of salt were sold across India, each sourced from just one region: this quirk allowed him to use local differences in the price of salt to calculate transport…Continue reading
Rescuing Myanmar’s farmers from the debt trap
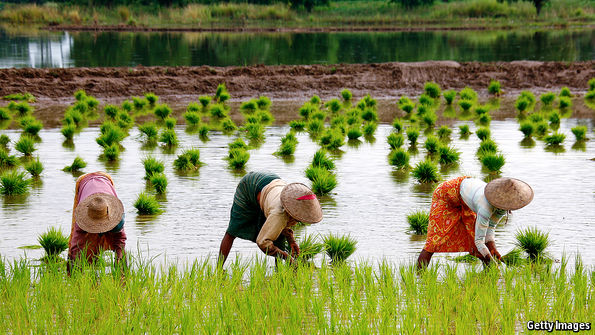 Living on borrowed rice
WHEN Myo Than was a young man, his family had 12 hectares of farmland in Dala, a rural township just across the river from Yangon, Myanmar’s biggest city. His mother sold most of it after his father died. Mr Myo Than grows rice on what’s left, but water shortages mean he reaps just one harvest each year. He borrows money from the Myanmar Agricultural Development Bank (MADB)—1.5m kyats ($1,100) this year, at an annual rate of 8%—to cover planting costs. But rice is a low-return crop. To repay the bank he borrows from local moneylenders at a rate of around 4% each month. Mr Myo Than owes them $7,300. He has given his land deeds to a moneylender as security.
Mr Myo Than’s predicament is not unusual: poor crop returns and usurious loan terms have kept Myanmar’s farmers trapped in poverty and debt. Around 60% of Myanmar’s population are engaged in agriculture. Most are poor, and farm small plots of land using age-old manual techniques. Farmers scythe rice fields; water buffaloes pull wooden ploughs; hay-laden bullock-carts trundle down narrow roads.
Many farmers borrow to cover planting costs, buy equipment…Continue reading
The EFTA countries show how hard Brexit will be for Britain

NORWAY offers much to envy. The food is tasty, public services are great and the people are impossibly good-looking. Its trade policy looks equally desirable. Though it trades heavily with the EU, Norway can also strike trade deals all over the world, either operating in concert with the three other members of the European Free Trade Association (Iceland, Liechtenstein and Switzerland) or on its own. Members of EFTA have dozens of deals, including two with China, with which the EU cannot even start negotiations.
After it leaves the EU, Britain will look much like an EFTA country: a rich economy with close links to Europe, but also seeking trade deals elsewhere. It is superficially an attractive prospect. Yet EFTA’s half-in-half-out relationship with the EU hinders its trade as much as it helps.
EFTA’s flexibility in trade stems from its odd relationship with the EU. Switzerland has a series of bilateral agreements, whereas Norway, Iceland and Liechtenstein are part of the single market through the European Economic Area (though with opt-outs for agriculture and fisheries). Crucially, however, all are outside the EU’s customs union, an agreement which regulates…Continue reading
A different approach to mobile money in Africa
WITH her phone in one hand and a live chicken in the other, Brenda Deeomba comes for her money. Her husband is a builder in Lusaka, the Zambian capital, and sends his wages home through Zoona, a money-transfer company. She receives them at a roadside booth in Chongwe, a nearby town, using a PIN number sent to her phone. It is a safe way to get the money, says Ms Deeomba, above muffled squawks.
Money-transfer businesses are proliferating in Africa. But Zoona is unusual. Unlike M-PESA, the best-known, in Kenya, it is not run by a phone company. Nor is it owned by a bank. Instead, Zoona has built a business from scratch. It processed $200m in transactions last year and bubbles with ambition: Mike Quinn, its (Canadian) chief executive, talks of reaching 1bn customers.
Zoona was founded in Zambia in 2009 by two brothers, Brad and Brett Magrath. As a startup, they were at a disadvantage, having to recruit their own agents. Zoona did so by seeing them as its core customers, giving them credit and training to set up their own franchises. Some are impressively successful. In central Lusaka, Misozi Mkandawire presides over an empire of kiosks. She started with Zoona while at college. Her profits can now reach 50,000 kwacha ($5,200) a month. That is exceptional. Last year the average agent made $548 in monthly commission, before costs. Globally, nearly half of…Continue reading
The boss of scandal-plagued Barclays gets into trouble himself

IN HIS first 17 months running Barclays, Jes Staley seemed scarcely to put a foot wrong. The American has narrowed the British lender’s ambitions, to focus on retail business at home, corporate and investment banking on both sides of the Atlantic, and credit cards. He is pulling Barclays out of Africa, after a century, and has sped up its retreat from other markets. He has also poached several folk from JPMorgan Chase, where he spent 34 years and ran the investment bank.
On April 10th it emerged that Mr Staley had clumsily planted a boot out of bounds. Last June Barclays’ board and an executive received anonymous letters about a “senior employee” hired earlier in 2016. These, say the bank, raised concerns “of a personal nature” about this person and Mr Staley’s role in dealing with the matter “at a previous employer” (presumably JPMorgan Chase).
Mr Staley, seeing the letters as “an unfair personal attack” on the newcomer, asked Barclays’ security team to find out who had written them, but was told that this should not be done. In July he inquired whether the matter was resolved—and formed the “honestly held, but mistaken” belief…Continue reading
A new mood of optimism infects investors in China’s banks
GUO SHUQING, China’s new banking regulator, knows the enormity of his task. China’s banking system, he observed last month, is worth more than $33trn. So it is bigger than any other country’s, and even than Europe’s as a whole. And he is well aware of the pitfalls left by a decade of breakneck lending growth. But if Mr Guo is nervous, he is hiding it. “All problems and contradictions will be resolved,” he says.
Of course, a Chinese official can be expected to express confidence about Chinese banks. More surprising is that a small but growing number of analysts and investors seem to concur. Chinese bank shares are up by a quarter since early last year. One investment bank, Morgan Stanley, has declared that China’s lenders are “in a sweet spot”. Another, Goldman Sachs, has upgraded China to “overweight”—that is, recommending that clients buy Chinese shares—and is especially positive about the banks. Shanghai Financial News, a local newspaper, described the new mood around these giant institutions as the “return of the king”. The question is whether it will be a long, stable reign or a short-lived, turbulent one.
The…Continue reading
The mysterious quiescence of the gold market

AMERICA has bombed Syria, and its relations with Russia have deteriorated. North Korea is developing a long-range nuclear missile, a development which Donald Trump has vowed to stop, unilaterally if necessary. There is talk of a “reflation trade”, with tax cuts in America pepping up global growth.
All this ought to be good news for gold, the precious metal that usually gains at times of political uncertainty or rising inflation expectations. But as the chart shows, gold took a hit when Mr Trump was elected in November and is still well below its level of last July. As a watchdog, gold has failed to bark.
Bullion enjoyed a ten-year bull market from 2001 to 2011, when it peaked at $1,898 an ounce. This long upward run was bolstered in its later stages by two developments: first, the use of quantitative easing (QE) by central banks, which gold bugs argued would inevitably lead to high inflation; and second by the euro crisis, which caused nervousness about the potential for a break-up of the single currency and about the safety of European banks. By 2013, however, euro-zone worries were fading and, despite QE, no inflation had been seen. The gold…Continue reading
Why the Federal Reserve should keep its balance-sheet large

HOW much money should exist? The Federal Reserve must soon confront this deep question. The Fed has signalled that towards the end of 2017 it will probably begin to unwind quantitative easing (QE), the purchase of financial assets using newly created bank reserves. The central bank’s balance-sheet swelled from about $900bn on the eve of the financial crisis to about $4.5trn by 2015 as it bought mortgage-backed securities and government debt (see chart). If and when the Fed shrinks its balance-sheet, it will also retire the new money it created.
Economists such as Milton Friedman popularised the study of the quantity of money in the 1960s and 1970s. By the financial crisis, however, the subject had gone out of fashion. The interest rate, it was agreed, was what mattered for the economy. The Fed varied the supply of bank reserves, but only to keep rates in the market for interbank loans where it wanted them to be.
The Fed’s injection of emergency liquidity into financial markets in 2008, however, sent interest rates tumbling. To regain control, it started paying interest on excess reserves (ie, those reserves in excess of those required by regulation)….Continue reading