
Tag: FINANCE
How the shape of global banking has turned upside down
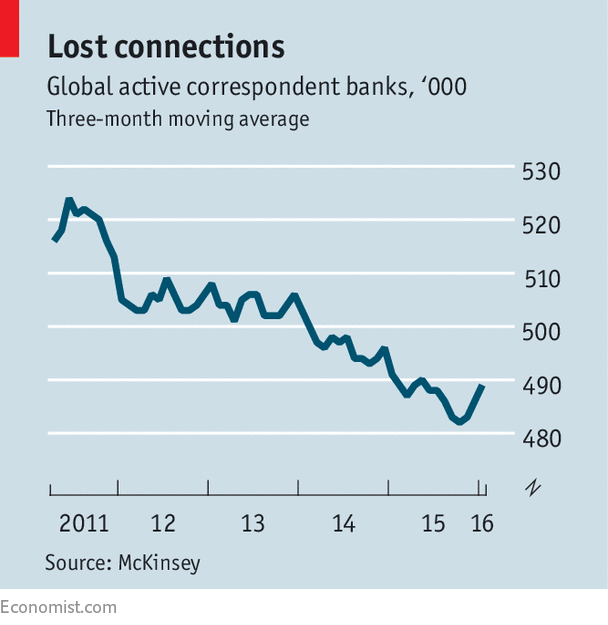
IN THE 1980s, when Citicorp was America’s largest bank and pursuing every avenue for international expansion, John Reed, the bank’s boss, would muse about moving its headquarters to a neutral location, notably the moon. Such sentiments are inconceivable today. Jamie Dimon, boss of JPMorgan Chase, Citi’s successor atop the league tables, recently said he is an American “patriot” first, head of a bank second. His strategy, though hardly shunning international markets, reflects this.
Mr Dimon turned down several big foreign acquisitions before and during the financial crisis. His stellar reputation may rest as much on those undone deals as on those completed. Citi, meanwhile, has been lopping off foreign affiliates. It has retail operations in just 19 countries, down from 50 in 2007. Further contraction may be in the offing. Bank of America has long chosen to live down to its name, as an almost entirely domestic bank.
The same process is under way in western Europe. Visible…Continue reading
Private-equity returns can be replicated with public shares
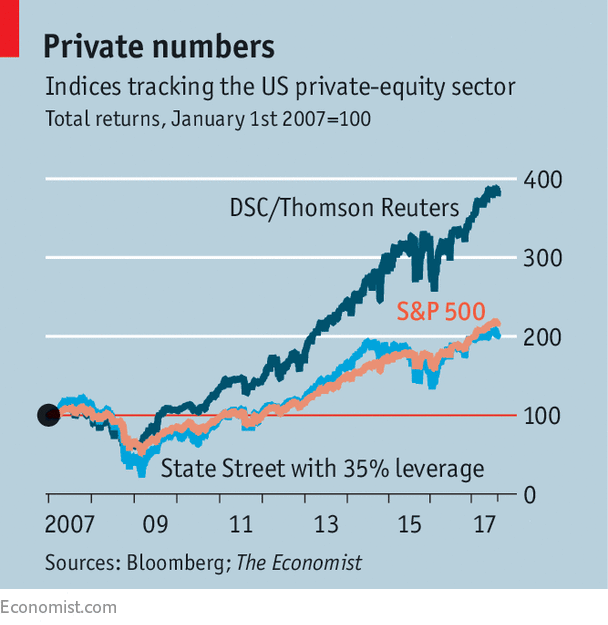
IT IS hard for individual investors to match the returns achieved by private-equity funds. But what if their success in outperforming the public markets could be tracked and replicated? A few pioneering firms claim to have done just that. DSC Quantitative Group, a Chicago-based fund, and State Street, an asset manager, both offer “investable” indices, launched in 2014 and 2015 respectively, that allow investors to mimic the performance of American private equity.
Both firms needed a measure of the industry’s returns. DSC teamed up with Thomson Reuters, a data firm, to compile an index; State Street had been making one since 2004, using data it gleans as a custodian of private-equity assets.
They then match the private-equity risk-and-return profile with a basket of public assets. DSC’s index first matches the sector weights of the private portfolio with equivalent public companies, and adds a modest amount of debt (around 25%) unevenly across the sectors—all using…Continue reading
Islamic banking grows in Bangladesh, no thanks to the authorities
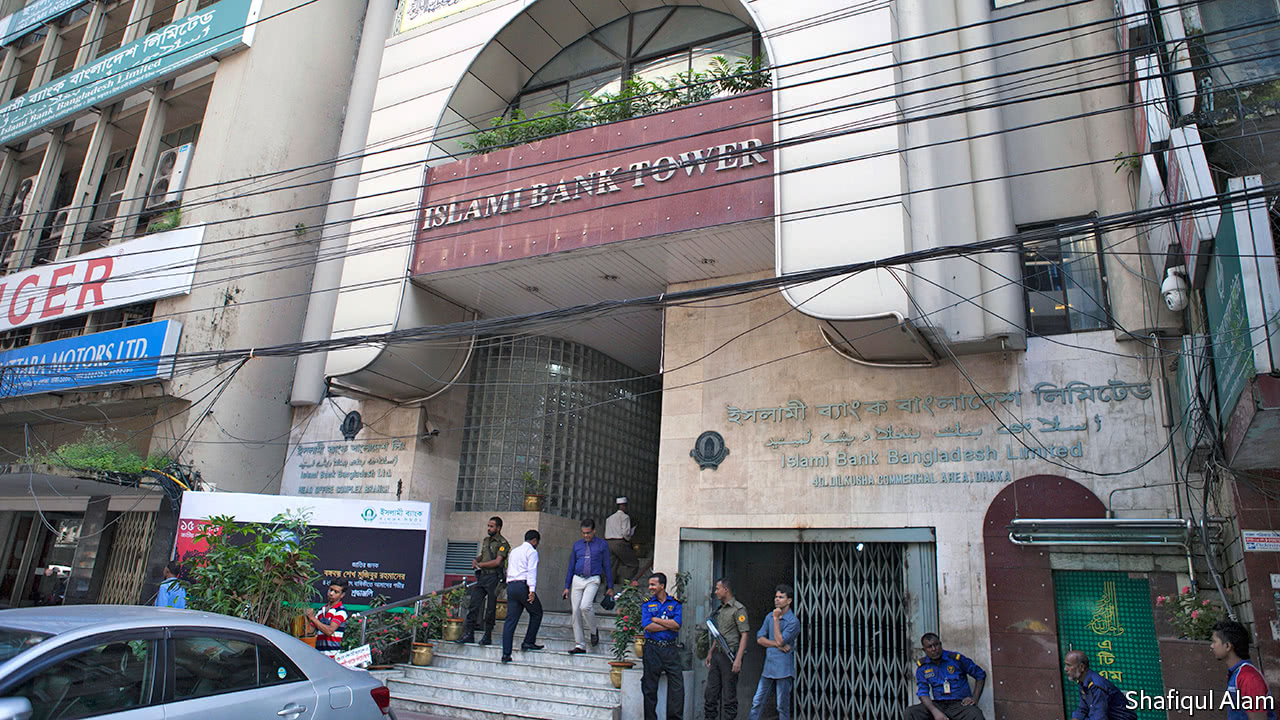
IN MOTIJHEEL, the main business district in Bangladesh’s capital, Dhaka, an iron fence and terrible traffic divide two branches of the country’s oldest private bank—a “conventional” one and an Islamic one. Abdus Sattar, manager of the Islamic one, says that when he joined AB Bank, in 2005, his was “a loser branch”. Today, like most Islamic banks in the country, it is more profitable and better run than its conventional peers. Islamic banking’s future in the country, however, remains murky.
Bangladesh has eight full-fledged Islamic banks; a handful of orthodox banks, like AB, also offer Islamic-banking services alongside others. Islami Bank Bangladesh, founded in 1983 by Saudi and Kuwaiti investors, commands 90% of Islamic-banking assets and deposits. It is also the biggest private lender overall, with 14,000 staff, 12m depositors and a balance-sheet of $10bn. Its success was built on the “two Rs”: remittances…Continue reading
The “free” economy comes at a cost
FACEBOOK, whose users visit for an average of 50 minutes a day, promises members: “It’s free and always will be.” It certainly sounds like a steal. But it is only one of the bargains that apparently litter the internet: YouTube watchers devour 1bn hours of videos every day, for instance. These free lunches do come at a cost; the problem is calculating how much it is. Because consumers do not pay for many digital services in cash, beyond the cost of an internet connection, economists cannot treat these exchanges like normal transactions. The economics of free are different.
Unlike conventional merchants, companies like Facebook and Google have their users themselves produce value. Information and pictures uploaded to social networks draw others to the site. Online searches, selections and “likes” teach algorithms what people want. (Now you’ve bought “The Communist Manifesto”, how about a copy of “Das Kapital”?)
The prevalence of free services is partly a…Continue reading
The Catholic church becomes an impact investor
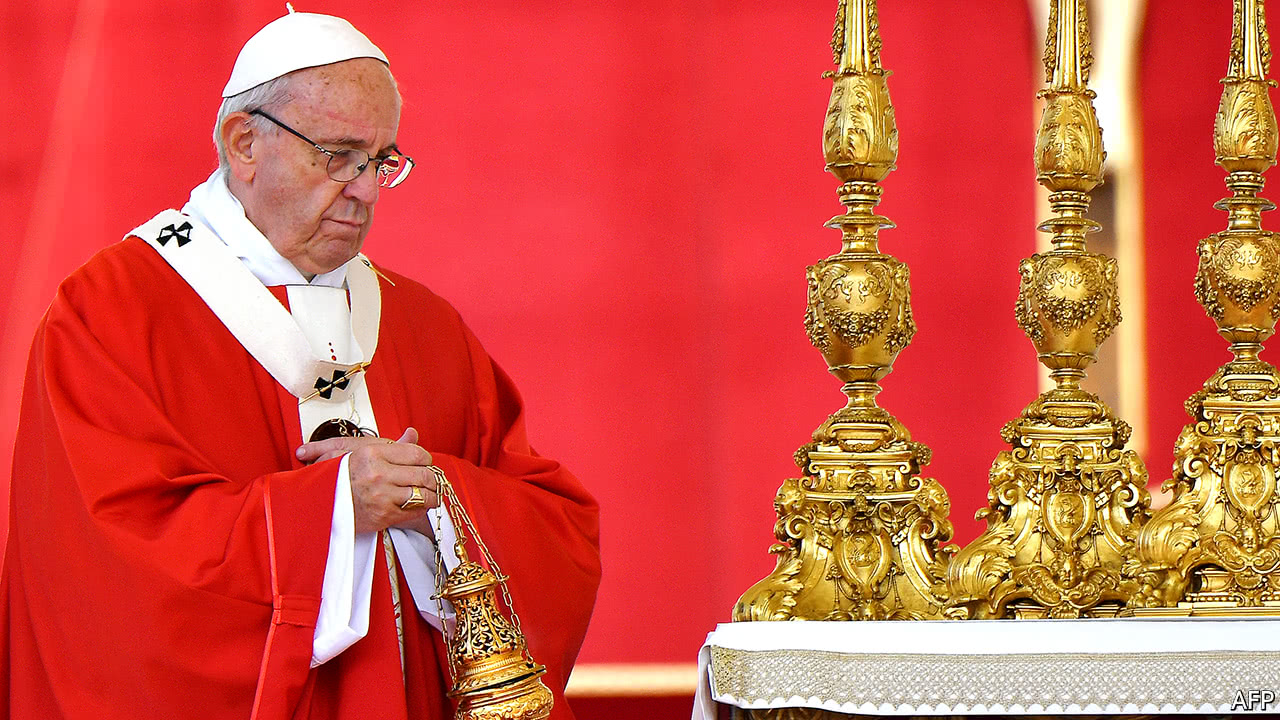
“YOU cannot serve both God and money,” admonishes the Bible. But the church has always tried. In the Middle Ages monasteries were what would now be termed social enterprises. They would produce bread, books or other goods. A Franciscan monk is credited with codifying double-entry book-keeping.
These days the Catholic church and related institutions control many billions of dollars. Some is invested to earn income; some is given away for good works. The two activities have been seen as separate. But, in the pontificate of Pope Francis, that divide is blurring. “Impact” investing—intended to make money and do good at the same time—is growing in importance. It is also creating some controversy.
In 2014 the pope, speaking to a conference in the Vatican on impact investing, called on Christians to rediscover “this precious and primordial unity between profit and solidarity”. His church has responded. Some…Continue reading
China modernises its monetary policy
QIN SHIHUANG was the emperor who first unified China, through bloody conquest more than two millennia ago. Known for starting the Great Wall and burying scholars alive, he has a new claim to fame: the central bank has drawn on his construction of a national road system to help explain its new monetary system. In a report on August 11th, the People’s Bank of China seized on an idiom derived from his road-building experience: it had “shaved off mountain peaks and filled valleys” in managing liquidity.
The modernisation of monetary policy is in its own way a monumental project for China. Over the past two decades, the central bank’s conduct of policy had two defining features. It focused on the quantity, not the price, of money. And it relied on inflows of foreign cash to generate new money. Both features are now slowly changing, bringing China closer to the norm in developed markets, an essential transition for an increasingly complex economy.
Start with interest rates. These used to be of secondary importance in China. Regulators instead used quotas to dictate how much banks lent and in effect fixed their deposit and lending rates. This made sense when China was in the early stages of moving away from a planned economy. Crude targets were still needed. But as a bigger, rowdier financial system took shape, these targets became less relevant. With the…Continue reading
The Trump administration is investigating Chinese trade practices

BEING tough on China was a constant theme of President Donald Trump’s election campaign. On August 14th he had another chance to wield his presidential pen to show that he is making good on his promises—in this case of a “zero-tolerance policy on intellectual-property theft and forced technology transfer”. With the cameras rolling, he formally instructed Robert Lighthizer, the United States Trade Representative, to consider launching an investigation into China’s alleged crimes. “This is just the beginning,” was Mr Trump’s final flourish for the news bulletins.
His record of translating signatures into policies is patchy. Two others, launching investigations into whether imports of steel and aluminium threaten America’s national security, seem to have fizzled. But whereas proposals for import restrictions on these commodities met fierce resistance from consumers and America’s allies, China’s trade practices provoke much more agreement. It is one of the few…Continue reading
The North American Free-Trade Agreement renegotiation begins
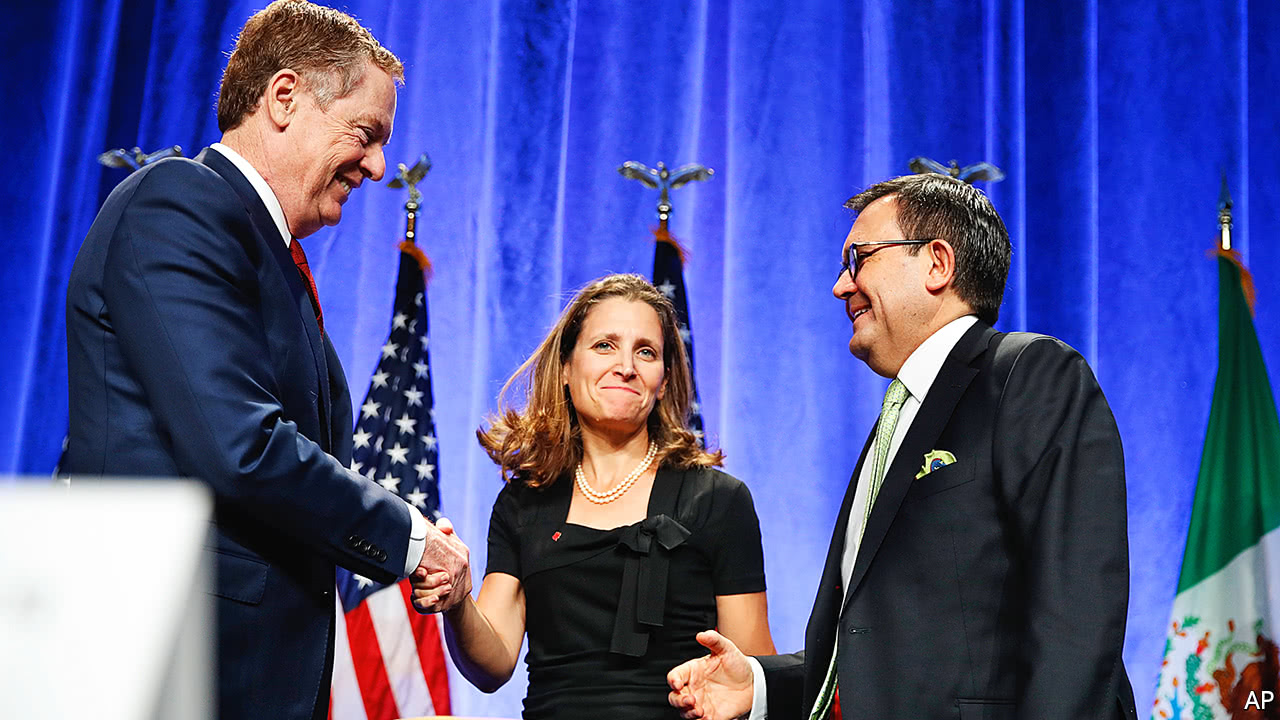
THE North American Free-Trade Agreement (NAFTA), a 23-year-old trade deal between America, Mexico and Canada, is being revamped. On August 16th, after months of threats, taunts and tweets, the first round of talks started in Washington. The negotiators face a daunting challenge, straddling domestic and foreign policy. They must please their political masters while grappling with devilishly detailed policy problems. If they fail, it will not be for lack of experience. The professionals are in the room.
This negotiation will be more tense than most. Participation in trade talks is usually by mutual consent. In this one, President Donald Trump is trying to hold his trade partners hostage, by threatening to withdraw from the original deal if a better one cannot be agreed on. That such an outcome would also hurt America does not make the exercise any easier.
Pressure is added by a desperately tight, if unacknowledged, deadline, set by the presidential-election timetable in Mexico….Continue reading
Hedge funds try to promote sports betting as an asset class

WHEN he was 12, Warwick Bartlett bought “100 Famous Greyhound Systems”, a guide for betting on dog races. After spending a year tracking every stratagem and picking the best two, he went to the races to take his first punts. He lost. Mr Bartlett, now the boss of GBGC, a betting consultancy, says it taught him a good lesson: “A system can win for a period of time. And then it’s had its day.”
Two trading companies are trying to prove him wrong. Melbourne-based Priomha Capital, which claims to be the “world’s premier sports hedge fund”, wagers on European football, cricket and golf. Founded in 2010, the firm manages about $20m. Stratagem, a rival based in Britain that styles itself as a technology business, wants to raise $25m from rich individuals.
Both argue that techniques imported from the investment world can help turn sports betting into an alternative asset class. By crunching data, they analyse the pricing…Continue reading
Why Africa’s development model puzzles economists
IT IS easy to buy a rolex in Uganda—albeit not one that will tell the time. Sold at ubiquitous roadside stalls, the Ugandan rolex is a greasy snack, made from an omelette wrapped in a chapati (“roll eggs”). Sellers compete side-by-side for the same custom. So do the motorcycle-taxi drivers, hustling for rides; or the countless small shopkeepers, stocking near-identical goods. In Uganda, as in much of Africa, the informal service economy is a crowded place to be. But it is hard to find work anywhere else.
Last year GDP in sub-Saharan Africa grew by just 1.4%. Income per person fell. But growth in itself is not the issue that troubles policymakers and intrigues academics: for most of this century, after all, African economies have been among the fastest-growing in the world. What has flummoxed observers is where that growth comes from. In 1954 Arthur Lewis, a Nobel prize-winning economist, argued that development occurs as labour shifts from an unproductive…Continue reading