
Tag: Approved
A weak market for football rights suggests a lower value for sport

FOR years the cost of rights to broadcast major sports in America and Europe has trended in one direction—up. This gravity-defying law shapes the economics of modern sport: as television operators bid ever more substantial sums, teams take in more revenue and star-player salaries (and transfer fees) climb higher. In 2017 that trajectory continued as broadcasters splurged on rights for Champions League football matches for 2018-21.
This year gravity is reasserting itself. Top-flight football rights are out for tender in two major European leagues—England and Italy—and are expected to be put up for sale this year in France and Spain, too. Analysts expect relatively small increases in pay-outs (though Spain’s La Liga boss predicts a 30% rise)—and possibly a decline in Italy. “The happy days are over,” says Claire Enders of Enders Analysis, a research firm.
The chief problem is fundamental weakness at the bidding…Continue reading
Masayoshi Son may raise yet more cash to pump into tech

AT AN investor briefing in 2015, Masayoshi Son, chief executive of SoftBank, flashed up a picture of a goose. The company is like the bird of legend that produces golden eggs, he explained. In his quest to encourage more laying, Mr Son has taken SoftBank well beyond its telecoms business. The firm also manages the world’s largest tech-investment fund, the $100bn Vision Fund, which has a slew of wealthy backers, including Saudi Arabia’s Public Investment Fund and Apple.
Using both the firm and the fund, Mr Son has acquired stakes in tech companies at a frenetic pace, by one count opening his chequebook once every four days on average in 2017. Such shopping sprees do not come cheap. SoftBank is one of Japan’s most highly leveraged companies, with debt exceeding ¥15trn ($139bn), not least because of its purchase in 2013 of a controlling stake in Sprint, an American mobilenetwork operator.
News reports this week suggest SoftBank is now hatching a plan to raise ¥2trn by…Continue reading
Innovative materials from bamboo are helping a new industry to sprout
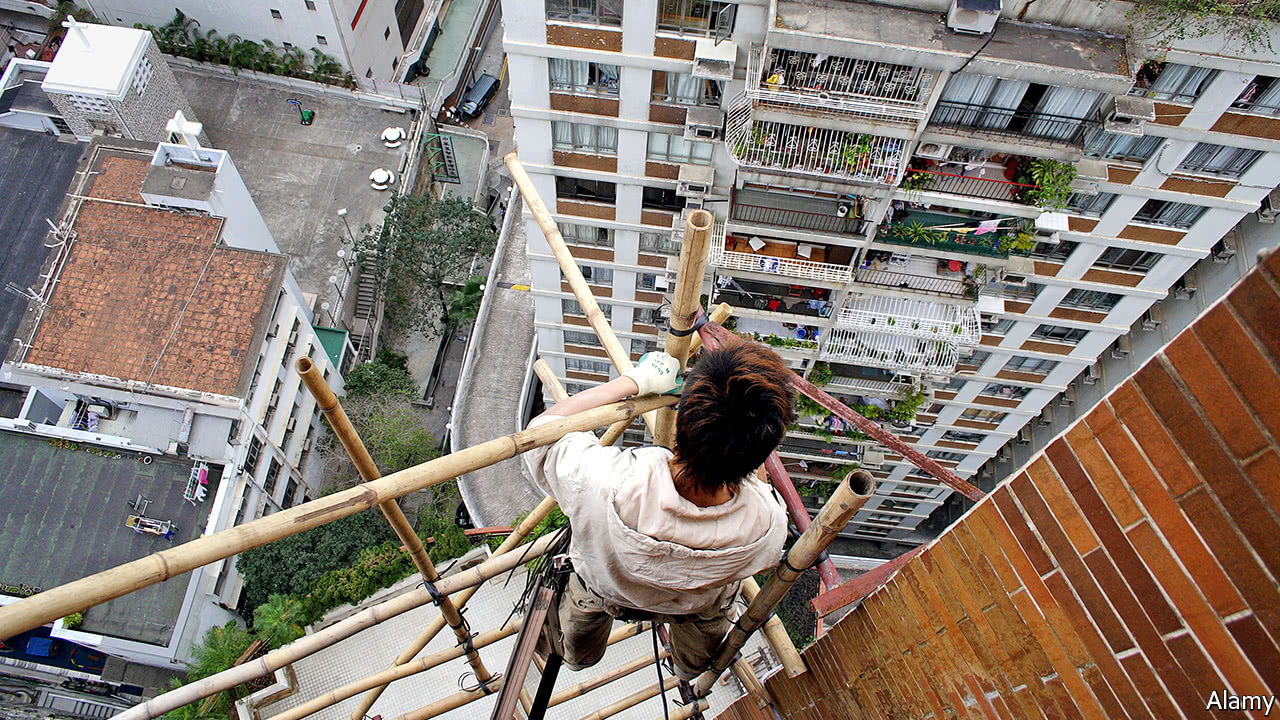
FANNING out from the sodden delta of the Yangtze, and southward to the flanks of the Nanling mountains, over 6m hectares of emerald bamboo groves—one-fifth of the world’s reserves—flourish in China. Giant pandas nibble the softest shoots. Around 40bn pairs of disposable chopsticks are made from bamboo twigs annually in China, for use with everyday meals. Steel scaffolding is still often shunned for bamboo on skyscrapers under construction in even the ritziest parts of Hong Kong. The history of the grass is colourful, too. Before paper, Chinese wrote on bamboo slips; they used bamboo tubes for irrigation, and later stuffed them with gunpowder to ignite muskets.
Yet for all its importance and abundance bamboo is “China’s forgotten plant”, says Martin Tam, an expert in Hong Kong. To demonstrate its potential, he greets visitors with a can of bamboo juice, proffers a bamboo business card, and gestures to a bamboo armchair near his desk….Continue reading
Chinese tech companies plan to steal American cloud firms’ thunder

WHICH of the world’s tech giants boasts the fastest-growing computing cloud? Many would guess either Amazon or Google, which operate the world’s largest networks of data centres, but the correct answer is Alibaba. In 2016 the cloud-computing business of the Chinese e-commerce behemoth grew by 126%, to $675m. Growth is unlikely to slow soon. Simon Hu, president of Alibaba Cloud, wants it to “match or surpass” Amazon Web Services (AWS) by 2019.
That is a stretch: AWS is estimated to have generated revenues of about $17bn in 2017. But Alibaba’s cloud (known locally as Aliyun) is one of a thriving group: China’s cloud-computing industry as a whole is growing rapidly. Even more intriguing than its speedy expansion is the fact that China’s cloud is different to that of Western firms in important ways.
The technology that China’s cloud-computing providers use is not so dissimilar. Indeed, the fact that Western tech firms have released much of the necessary code as open-source…Continue reading
After a huge loss on old reinsurance contracts, GE contemplates a break-up
DECISIONS made long ago, and often long since forgotten, can come back to haunt. General Electric (GE), an American industrial conglomerate, has discovered that to its chagrin. On January 16th the company said it would have to take a $9.5bn charge (before tax) on old reinsurance contracts in its financial arm, GE Capital—despite exiting the insurance business in the mid-2000s. The firm also said it would have to set aside up to $15bn of additional reserves for GE Capital over seven years. The conglomerate had already been struggling, with its share price down by over 40% in the past year. News of the latest hit, which the company’s chief executive, John Flannery, called “deeply disappointing”, sent its shares plunging by a further 3% on January 16th alone.
The issue at hand concerns reinsurance contracts in GE Capital’s American life- and health-insurance portfolio. Jack Welch, an idolised former GE boss, had massively expanded the…Continue reading
How China won the battle of the yuan
“THE horse may be out of the proverbial barn.” So wrote Ben Bernanke, a former chairman of the Federal Reserve, in early 2016, arguing that capital controls might be powerless to save China from a run on its currency. He was far from alone at the time. As cash rushed out of the country, analysts debated whether the yuan would collapse, and some hedge funds bet that day was coming fast. But two years on, the horse is back in the barn: the government’s defence of the yuan has succeeded, in part through tighter capital controls.
The latest evidence was an 11th consecutive monthly increase in foreign-exchange reserves in December. During that time China’s stockpile of official reserves, the world’s biggest, climbed by $142bn, reaching $3.14trn, roughly double the cushion usually regarded as needed to ensure financial stability. Another sign of China’s success is the yuan itself. At the start of 2017 the consensus of forecasters was that the currency would continue to weaken; it finished the year up by 6% against the dollar.
Investors and analysts were not wrong in viewing Chinese capital controls as porous. Enterprising types had—and have—umpteen ways to sneak money out, from overpaying for imports to smuggling cash across the border in luggage. But there is a wide spectrum between a fully open and fully closed capital account, and China has…Continue reading
Having rescued recorded music, Spotify may upend the industry again
IN JUST a few short years Spotify has evolved from bête noir of some of the world’s most prominent recording artists to perhaps their greatest benefactor. The Swedish company transformed the way people listen to music, and got them used to paying for it again after digital piracy had crippled sales. Global revenues from music streaming, which Spotify dominates with 70m subscribers, more than tripled in three years, to an estimated $10.8bn last year, for the first time surpassing digital and physical sales of songs and albums.
But if it is earning billions for others, Spotify is losing money for itself—with an operating loss of nearly $400m in 2016—because it pays out at least 70% of its revenues to the industry, mostly in royalties. As it prepares for a “direct” listing on the New York Stock Exchange (see article) it must convince…Continue reading
Companies are moving faster than many governments on carbon pricing
ECONOMISTS have long argued that the most efficient way to curb global warming is to put a price on the greenhouse-gas emissions that cause it. A total of 41 OECD and G20 governments have announced either a carbon tax or a cap-and-trade scheme, or both. Add state and local schemes, and they cover 15% of the world’s emissions, up from 4% in 2010. Voters concerned about climate change are egging them on. So, too, are corporate bosses. More firms are imposing such pricing on themselves, even in places where policymakers are dragging their feet.
Of the 6,100-odd firms which report climate-related data to CDP, a British watchdog, 607 now claim to use “internal carbon prices”. The number has quadrupled since CDP first began posing the query in its annual questionnaire three years ago. Another 782 companies say they will introduce similar measures within two years. Total annual revenues of these 1,389 carbon-price champions amount to a hefty…Continue reading
Taiwanese bosses are the Chinese-speaking world’s oldest
DESPITE her father’s pleas, Cherry Liu refused to work for the family business, a small electronic-components company founded in 1979 on the outskirts of Taipei. A 34-year-old diamond dealer based in Sydney, Ms Liu says she is simply not passionate about gadgets such as circuit-breakers. Nor are her siblings. Her 64-year-old father cannot find a successor, but he will not even consider recruiting someone outside the family, she says. He fears that a newcomer might leave and take the family’s precious list of customers and suppliers with him.
Taiwan’s economic boom was fuelled by people like Ms Liu’s father, entrepreneurs who started from nothing to build successful family-run companies, many of which are now huge. These firms still dominate Taiwan’s export-reliant economy, which specialises in high tech. Of all listed firms, 70% are family-run, compared with 33% for Chinese firms and 40% for Hong Kong-based ones. Almost three-quarters of family concerns are operated…Continue reading
Spotify opts for an unusual way of going public
FOR seasoned bankers and starry-eyed entrepreneurs alike, doing an IPO, or initial public offering, is synonymous with the very idea of taking a firm public. No wonder, then, that the decision by Spotify, a music-streaming service, to opt for an unconventional alternative called a “direct listing” has prompted debate. Instead of paying investment banks hefty fees to arrange an IPO, Spotify plans to have existing shares simply switch one day to being tradable on the New York Stock Exchange (NYSE).
IPOs themselves have become rarer, as startups such as Uber and Airbnb have chosen to raise money through private markets instead. Although there was an uptick in the number of IPOs in America in 2017—108, compared with 74 in 2016—the average number of IPOs has remained at around 100 annually since 2000, compared with over 300 in the course of the two previous decades. But until now no big company had contemplated direct listing as an alternative. The structure has been seldom used: in…Continue reading