
Tag: Approved
The parable of St Paul

PAUL POLMAN runs Europe’s seventh-most valuable company, Unilever, worth $176bn, but he is not a typical big cheese. A Dutchman who once considered becoming a priest, he believes that selling shampoo around the world can be a higher calling and detests the Anglo-Saxon doctrine of shareholder primacy, which holds that a firm’s chief purpose is to enrich its owners. Instead Mr Polman preaches that companies should be run “sustainably”—by investing, paying staff fairly, and by making healthy products with as little damage as possible to the environment. This is actually better for profits in the long run, he argues: society and shareholders need not be in conflict.
Mr Polman’s beliefs were tested in February when Unilever received a bid from Kraft-Heinz, a ketchup-to-hot dog gorilla controlled by Warren Buffett and 3G Capital, a fund known for ripping costs out of multinationals. If, in its own mind, Unilever is a good corporate citizen, then it sees Kraft as an angry American…Continue reading
Analysts struggle to make accurate long-term market forecasts

WHAT is the right way to invest for the long term? Too many people rely on past performance, picking fund managers with a “hot” reputation or backing those asset classes that have recently done well. Just as fund managers cannot be relied on to be consistent, returns from asset classes are highly variable. The higher the initial valuation of the asset, the lower the future returns are likely to be.
That is pretty clear with government bonds. Anyone buying a bond with a yield of 2% and holding it until maturity can expect, at best, that level of return (before inflation) and no more. (There is a small chance the government might default.) With equities, the calculations are not quite so hard-and-fast. Nevertheless, it is a good rule-of-thumb that buying shares with a low dividend yield, or on a high multiple of profits, is likely to lead to lower-than-normal returns.
So a sensible approach to long-term investing would assess the potential returns from asset classes, given their…Continue reading
Market concentration can benefit consumers, but needs scrutiny

WHEN Amazon announced in June that it would buy Whole Foods, an upmarket grocer, for $13.7bn, other firms shuddered. The spread of Amazonian tentacles is worrying to those wary of concentrated corporate power. But shoppers entering their local Whole Foods these days find oddly low prices alongside the new stacks of Echoes, Amazon’s voice-activated digital helpmate. This raises a question. Is Amazon hellbent on building a world-straddling monopoly, or merely injecting innovation and competition into yet another new market? For antitrust regulators, the welfare of the consumer is the priority. Yet working out how to protect it is harder than ever.
Competitiveness in most industries is a matter of degree. In the idealised marketplace of economics textbooks, the price people pay for goods equals the cost of producing an additional unit. Any higher, the theory goes, a competitor could cut the price a smidgen, sell another unit and profit. Yet outside commodity markets, most firms can charge…Continue reading
The gap between India’s richer and poorer states is widening
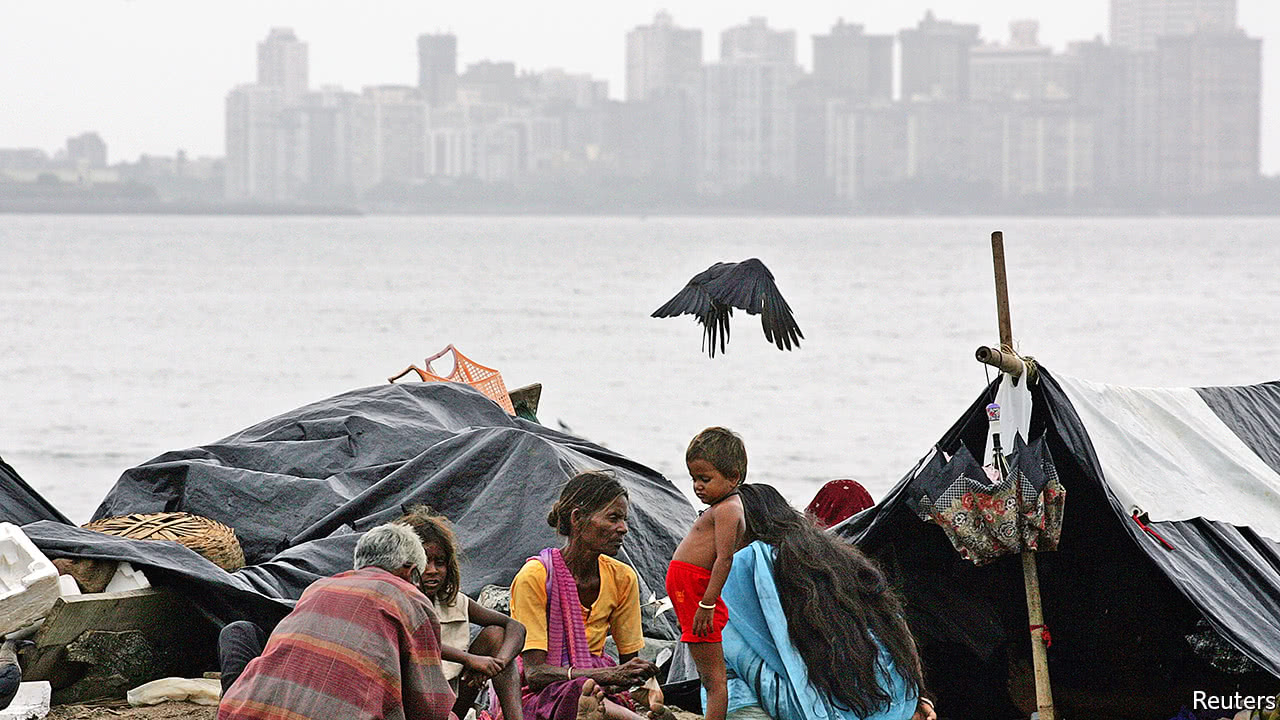
COUNTRIES find it easier to get rich once their neighbours already are. East Asia’s growth pattern has for decades been likened to a skein of geese, from Japan at the vanguard to laggards such as Myanmar at the rear. The same pattern can often be seen within big countries. Over the past decade, for example, China’s poorer provinces have grown faster than their wealthier peers. India is different. Far from converging, its states are getting ever more unequal. A recent shake-up in the tax system might even make matters worse.
Bar a few Mumbai penthouses and Bangalore startup offices, all parts of India are relatively poor by global standards. Taken together, its 1.3bn people make up roughly the third and fourth decile of the world’s population, with an income per person (adjusted for purchasing power) of $6,600 dollars. But that average conceals a vast gap. In Kerala, a southern state, the average resident has an annual income per person of $9,300, higher than Ukraine, and…Continue reading
Uber picks Dara Khosrowshahi as its new boss
“A LEADER is a dealer in hope,” said Napoleon. For much of this year Uber, a ride-hailing firm, has lacked both leadership and optimism. But on August 27th news leaked that Uber had poached as its new chief executive Dara Khosrowshahi, the boss of Expedia, an online travel company. Mr Khosrowshahi is seen as an astute dealmaker and a canny manager. In his 12 years at the helm of Expedia, the gross value of its hotel and other travel bookings more than quadrupled and its pre-tax earnings more than doubled.
Can he rally the troops? Uber is fast-growing and was last year valued privately by investors at around $68bn, but has suffered a host of setbacks, which led to the ousting of Travis Kalanick, its co-founder and boss, in June. The firm faces a criminal probe by America’s Department of Justice into a covert software feature that showed regulators different versions of its app, as well as a new investigation into whether it…Continue reading
Samsung’s boss is sentenced to prison
SAMSUNG’S founding family, the Lees, have good reason to dislike room 417 of Seoul’s Central District Court. In 2008 it was where Lee Kun-hee, the chairman of the sprawling South Korean conglomerate, was found guilty of tax evasion. On August 25th his son, Lee Jae-yong, the vice-chairman of Samsung Electronics, stood in the same room and was sentenced to five years in prison on charges including bribery, embezzlement and perjury. The elder Mr Lee has been in hospital since suffering a heart attack in 2014. Samsung now lacks both its official and de facto bosses.
The younger Mr Lee, who plans to appeal against the verdict, was accused of paying bribes to Choi Soon-sil, a confidante of the country’s former president, Park Guen-hye. Prosecutors had argued that he hoped the payments would secure government support for an $8bn merger of two Samsung affiliates, Cheil Industries, the group’s unofficial holding company, and Samsung C&T, a construction firm. The state-run National Pension Service, the single biggest shareholder in C&T, voted for the plan in July 2015. The deal was controversial, but it helped Mr Lee consolidate his control over the group and clear the way for his succession.
The decision is a milestone in a broader influence-peddling scandal that brought down Ms Park. She was impeached in March and arrested soon after; she now…Continue reading
American bosses continue to lobby, more quietly

IN CORPORATE America, “Trump” seems to be a dirty word, at least in public. After President Donald Trump seemed to equate the actions of white supremacists and their opponents in Charlottesville earlier this month, dozens of chief executives abandoned his advisory councils. Several organisations cancelled fundraising galas booked at Mr Trump’s Mar-a-Lago resort in Florida. Lloyd Blankfein, the boss of Goldman Sachs, an investment bank, compared Mr Trump to the dark shadow cast over parts of America by a solar eclipse: “We got through one, we’ll get through the other.”
Look past the public repudiation, though, and the schism is less stark. As Jason Furman of Harvard University’s Kennedy School, who led the White House Council of Economic Advisers during Barack Obama’s presidency, points out, the bosses’ public rejection of Mr Trump has done nothing to sap their appetite to guide policy. Lower-ranking executives from large firms continue to serve on informal…Continue reading
Does ageing explain America’s disappointing wage growth?
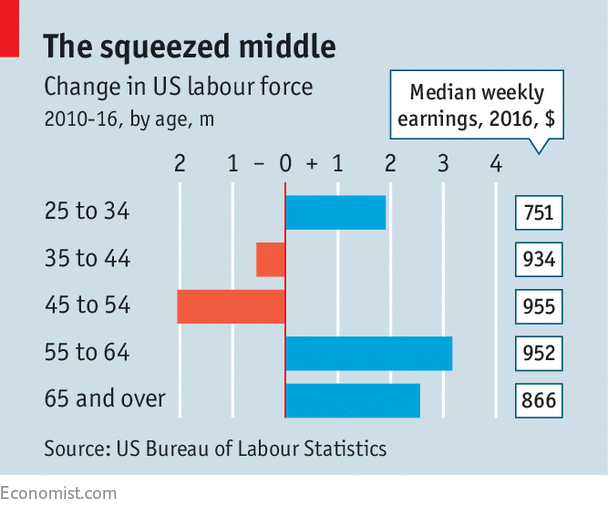
WHEN America’s unemployment was last as low as it has been recently, in early 2007, wages were growing by about 3.5% a year. Today wage growth seems stuck at about 2.5%. This puzzles economists. Some say the labour market is less healthy than the jobless rate suggests; others point to weak productivity growth or low inflation expectations. The latest idea is to blame retiring baby-boomers.
The thinking goes as follows. The average worker gains skills and seniority, and hence higher pay, over time. When he retires, his high-paying job will vanish unless a similarly-seasoned worker is waiting in the wings. A flurry of retirements could therefore put downward pressure on average wages, however well the economy does. The first baby-boomers began to hit retirement age around 2007, just as the financial crisis started. And since 2010, the first full year of the recovery, the number of middle-aged workers has shrunk considerably. They have been replaced partly by lower-earning youngsters (see…Continue reading
Management turmoil at Infosys is particularly ill-timed
THE quickest way to start a Mexican wave in India is to head to the campus of Infosys, an IT outsourcing firm based in Bangalore, and ask all those who think they should be in charge to raise their hands. On August 18th the company’s chief executive, Vishal Sikka (pictured), resigned unexpectedly. But he still serves as executive vice-chairman. Now a chairman, a co-chairman, the interim chief executive who succeeded Mr Sikka, the board of directors and a retired founder all seem to think they should be running the show. The stalemate risks leaving the firm without a leader just as it had started the urgent work of overhauling its business.
The company’s management crisis is surprising. As one of only a few Indian IT firms that multinational companies trust to build and maintain their computer systems, Infosys has long sought to exude an aura of professionalism bordering on the dull. But clashing egos at the top now make it seem anything…Continue reading
Are men more irrationally exuberant than women?
WOULD more women on the trading floor inject a dose of sanity into the world’s financial markets? This question gained prominence after the 2007-08 crisis. As Christine Lagarde, then France’s finance minister and now head of the IMF, quipped, had Lehman Brothers been Lehman Sisters, history would have been different. Many studies support this idea, showing that testosterone-laden men are prone to overconfidence in trading. Women are more cautious.
But things may not be so simple. Previous research has mostly used evidence from the West. To test if the conclusions apply universally, Wang Jianxin of China’s Central South University, Daniel Houser of George Mason University and Xu Hui of Beijing Normal University looked at both America and China. And they found that in China’s markets, women can be just as manic as men.
The economists arranged for 342 students to form experimental markets. They were allocated dividend-paying…Continue reading