
Tag: Approved
Deutsche Bank raises capital, and changes course
THREE times since the financial crisis, Deutsche Bank’s bosses have turned to its shareholders for cash: €10.2bn ($13.6bn) in 2010, €3bn in 2013 and €8.5bn in 2014. Since becoming chief executive in 2015, John Cryan has had no plans to ask for more. Deutsche still needed to thicken its equity cushion, but disposals, cost cuts and earnings (if any: it has made losses for the past two years) would provide the stuffing.
Well, plans change. On March 5th Mr Cryan announced an €8bn rights issue. Some comfort for investors: the price, €11.65 a share, is 39% below the previous close; and Mr Cryan, who had suspended the dividend, promises a return to “competitive” payouts next year. In another reversal, Deutsche will keep rather than sell Postbank, a mass-market retail business that was once part of the post office. Deutsche has owned it since 2010.
Postbank and the posher “blue” Deutsche Bank brand will be more closely integrated—notably, sharing computer systems. Mr Cryan is also selling a slice of Deutsche’s asset-management division and some lesser assets. And he is reorganising its corporate and investment bank to…Continue reading
Chinese startups push into foreign markets
 They’re coming your way
ON THE outskirts of Guangzhou, a city in southern China, lies an abandoned park filled with crumbling replicas of the wonders of the world. To the right are fading golden spires that are meant to represent Angkor Wat, a temple in Cambodia. On the left, a row of dusty Egyptian statues towers over a desolate Greek amphitheatre. Adding to the surrealism, the tops of the trees have been lopped off and a buzzing noise fills the night air.
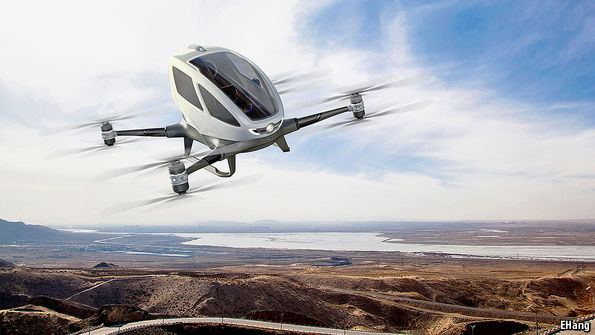
This strange place is the testing ground for EHang, a Chinese startup that makes drones. (The treetops were chopped off, an employee explains, because drones kept crashing into them.) Hu Huazhi, EHang’s founder, is beaming. His firm has just set a world record for a drone-swarm light show in Guangzhou, where it flew a thousand small drones in perfect unison. Next it plans to launch an autonomous flying-taxi service with a giant drone big enough to take a person (pictured). Dubai has just signed a deal with EHang to launch drone taxis this summer.
EHang is an example of a new kind of Chinese firm, labelled “micro-multinationals” by some. In the past,…Continue reading
The subdued mood in Singapore’s financial industry

SINGAPORE owes its existence, and its prosperity, to its place at the heart of intra-Asian trade. In more than 50 years of independence, the city-state has striven mightily to attract investment from all over the world. Such has been its success, indeed, that others hope to imitate its open, low-tax model. In Britain, for example, there has been talk of the country turning into a “European Singapore” once withdrawal from the EU is complete. (It would be a nice start if London’s Tube operated with anything like the same efficiency as Singapore’s subway network.)
The current mood in Singapore, however, is far less buoyant than you might imagine. Singapore has survived and thrived by steering a middle course between America and China. It has been alarmed both by the isolationist rhetoric of President Donald Trump and by recent, highly unusual, public spats with China.
Global trade growth has slowed in recent years. Despite signs of a pickup, this has had a big effect in a city that has the world’s second-busiest port and that (according to Barclays, a bank) is the country most exposed to the global value chains created by multinational…Continue reading
A big merger in the asset-management industry
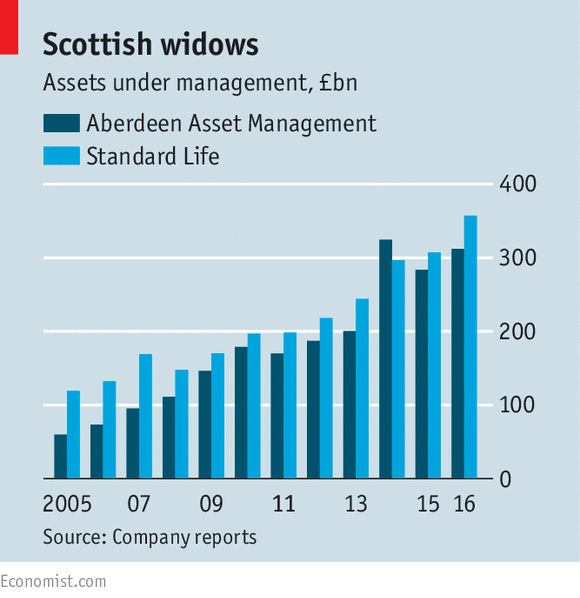
From fishing buddies to co-CEOs: that is how the relationship between Martin Gilbert, chief executive of Aberdeen Asset Management, and Keith Skeoch, his counterpart at Standard Life, will change after the companies this week announced plans to join forces. The merged company, to be based in Scotland, will have £660bn ($800bn) in assets under administration, making it Britain’s largest, and Europe’s second-largest, “active” asset manager.
Competition is forcing asset managers to consolidate. Henderson and Janus Capital teamed up last October; Amundi and Pioneer did the same in December. They hope to defend market share from fast-growing “passive” fund managers, whose funds track market indices rather than try to beat them, as active funds do. The research involved in trying to pick winners inevitably makes actively managed funds dearer than passive ones; once these costs are factored in, active managers tend to underperform passive ones. The fee gap is wide enough to have attracted scrutiny from British and European regulators: in Britain passive funds’ fees are around 0.15% of assets under management, compared with 0.9%…Continue reading
A New York startup shakes up the insurance business
 When insurance quickened the pulse
IT IS not typhoons or earthquakes that insurers should fear most, but geeks alert to their businesses’ inefficiencies. Daniel Schreiber and Shai Wininger, tech entrepreneurs with no insurance background, spotted that the industry is huge (worth $4.6trn in global premium income a year, reckons Swiss Re, a reinsurer), distrusted, antiquated and hopelessly unreformed.
In September they started Lemonade, a New York-based insurer for homeowners and renters. Some describe it as a peer-to-peer insurer (“Spiritually we’re a tech company,” says Mr Schreiber). Most agree that its app makes insurance a lot easier. This appeals to the digital generation: of 2,000 policies sold in its first 100 days, over 80% were to first-time buyers.
Insurance, the founders reasoned, suffers from misaligned incentives. Every dollar paid out comes from insurers’ pockets, encouraging poor behaviour. Normally upright people have few qualms about defrauding their insurer (as 25% of Americans do), pushing up premiums. Lemonade’s solution is to take 20% of premiums as a fee and to reward under-claiming…Continue reading
The coming revolution in insurance

IN THE stormy and ever-changing world of global finance, insurance has remained a relatively placid backwater. With the notable exception of AIG, an American insurer bailed out by the taxpayer in 2008, the industry rode out the financial crisis largely unscathed. Now, however, insurers face unprecedented competitive pressure owing to technological change. This pressure is demanding not just adaptation, but transformation.
The essential product of insurance—protection, usually in the form of money, when things go wrong—has few obvious substitutes. Insurers have built huge customer bases as a result. Investment revenue has provided a reliable boost to profits. This easy life led to a complacent refusal to modernise. The industry is still astonishingly reliant on human labour. Underwriters look at data but plenty still rely on human judgment to evaluate risks and set premiums. Claims are often reviewed manually.
The march of automation and technology is an opportunity for new entrants. Although starting a new soup-to-nuts insurer from scratch is rare (see
The end of “secular stagnation”?
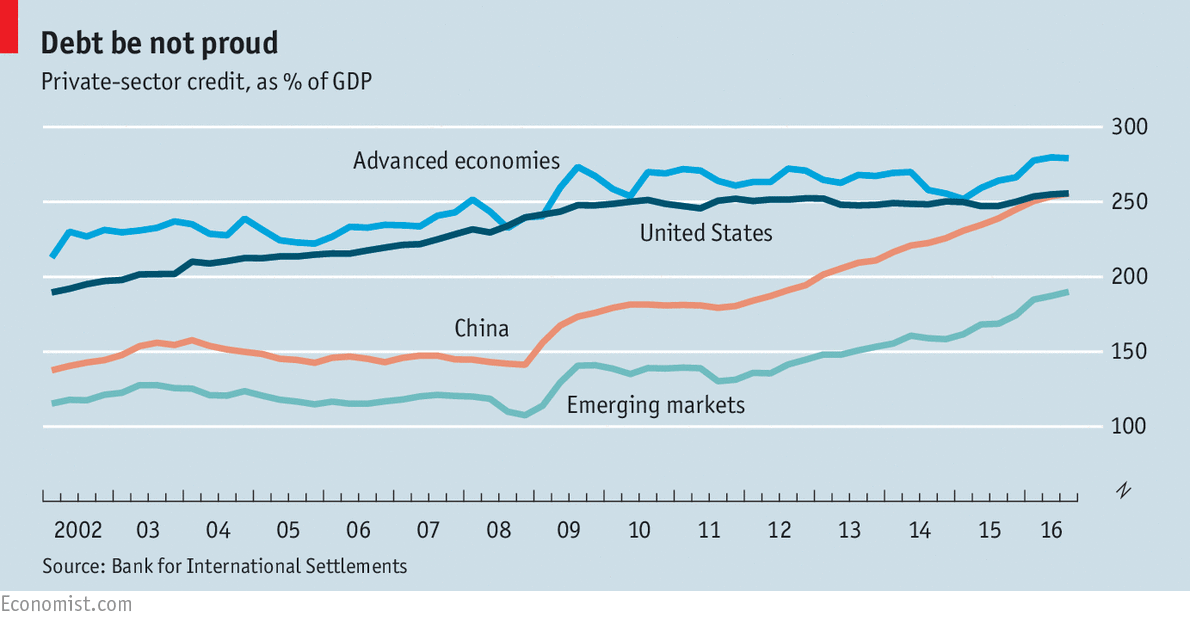
IN PERIODS of economic stress all sorts of theories are entertained about the nature of the problem. When better times return, some theories fade from memory. Others linger, however. During the economic mess of the past decade, economists frightened themselves with tales of “secular stagnation”: a nasty condition that dooms its victims to chronically weak growth. Now that the economic outlook is brightening a bit—deflation has been dispatched, and for most advanced economies 2017 is forecast to bring a third consecutive year of economic growth—it is tempting to laugh off the idea of secular stagnation as a bit of crisis-induced hysteria. Tempting, but also premature.
In a time of secular stagnation, the normal relationship between saving and investment goes haywire. People save some portion of their income each year. Because one person’s spending is another’s income, such saving can drain away demand and lead to recession, unless the funds set aside by savers are reinjected into the economy through lending to those looking to invest: as when banks lend savers’ deposits to businesses, for example. Central banks help manage this…Continue reading
A volatile start for shares in Snap
 Filter bubble?
WHEN Snap, the parent company of Snapchat, an app popular among teenagers for its disappearing messages, staged a public offering on March 2nd, Evan Spiegel, its 26-year-old boss, became a self-made billionaire. (Only John Collison of Stripe, an online payments startup, rivals him for such youthful tycoonery). Whether public-market investors will strike it rich remains to be seen. In its first day of trading Snap’s shares rose by 44%; they have since fallen by 16% from their peak, meaning around $5bn of market value vanished in days.
The volatility will probably continue. Optimists reckon that Snap’s market value could increase more than fourfold from around $26bn today as it adds users and advertisers. Very few large internet companies have gone public recently, which gives it tremendous scarcity value, says Roger Ehrenberg of IA Ventures, an early-stage investment firm.
But sceptics are growing in number. Every analyst who has started covering Snap’s stock has issued a negative rating. They question its high valuation and underline all the challenges. Snap’s growth has slowed in recent…Continue reading
Mukesh Ambani has made the business world’s most aggressive bet

SOME businesspeople are guided by experts, spreadsheets and crunchy questions. What is your three-year target for market share? Will a project deliver a reasonable return on the capital invested? A few hurl all the forecasts and reports into the bin and surrender to their own hunger to make a mark.
One such figure is Mukesh Ambani, India’s richest man. In September 2016 he placed one of the biggest business bets in the world by launching Jio, a mobile-telecoms network that allows India’s masses to access data on an unprecedented scale. In the past six months it has won 100m customers. Only one other firm on the planet has such an acquisition rate—Facebook. From Kolkata’s slums to the banks of the Ganges, millions of Indians are using social media and streaming videos for the very first time.
To achieve this, Mr Ambani has spent an incredible $25bn on Jio, without making a rupee of profit, terrifying competitors and many investors. The motivation for his gamble probably lies with his turbulent family history. Reliance Industries Limited (RIL), Mr Ambani’s company, was set up by his father, Dhirubhai, in 1957. Born in humble…Continue reading
The Trump administration’s trade strategy is dangerously outdated
 The trade guns of Navarro
ON THE campaign trail, Donald Trump’s trade policy was an alarming mixture of coruscating complaints and fierce threats of protectionist retaliation. But the world has been in the dark about how much of this rhetoric his administration might turn into reality. A flicker of light came on March 1st as the administration’s trade-strategy document was presented to Congress. Washington wonks see the hand of Peter Navarro, Mr Trump’s trade adviser and author of a book (and film) called “Death by China”. Robert Lighthizer, the nominee for the United States Trade Representative (USTR), has not yet been confirmed.
Little is new in the document’s promises of “ new and better trade deals” or of strict enforcement of American trade laws. But a preference for bilateral trade deals over multilateral ones is a change of tack. And the tone is certainly confrontational: “It is time for a more aggressive approach.” The document also gives an indication of how a Trump administration might take a trade fight to China: by using sections 201 and 301 of the Trade Act of 1974.
The first weapon,…Continue reading