
Tag: Finance and economics
Goldman Sachs announces a change in strategy

IT IS not easy to feel pity for Goldman Sachs. Its alumni lord it in pivotal government positions around the world; from every prestigious business school, applicants queue in hope of a job; its senior executives earn eye-watering amounts; and it has a presence, it seems, in every corner of the global economy. Yet these are troubling times for the bank. It is facing fundamental questions about its business model.
Its investors are particularly worried by a precipitous decline in the fortunes of its core fixed-income, currencies and commodities unit (FICC). That is the business from which Goldman’s current leadership graduated. The bank’s president, Harvey Schwartz, used a conference on September 12th to give an unusually detailed account of how it is changing. He outlined plans for igniting growth in an apparently stagnant business, and for preserving profitability despite that stagnation.
One factor in Goldman’s problems has been a change in its staff structure. In the hunt…Continue reading
Retail banks’ foreign ventures rarely pay off

NOT everybody—or every business—travels well. Retailers from Walmart to Tesco have faltered in forays into foreign lands. Banks, too, often fancy that success at home can be reproduced abroad. In meeting the needs of big companies, they are often right. Global corporations seem to want global banks. But in retail banking, serving households and small businesses, they are usually mistaken.
Or so concludes a report by Lorraine Quoirez and her colleagues at UBS, examining the performance of seven international banks (BBVA, Citigroup, HSBC, ING, Santander, Société Générale and Standard Chartered). For several measures, such as net interest margins and returns on equity, the Swiss bank’s analysts constructed benchmarks for each firm. The benchmarks are the averages for all banks in countries where the seven are active, weighted by the importance of each market in each bank’s loan book.
Most of the banks fall short on most measures. For example, UBS expects…Continue reading
The Fed prepares for its balance-sheet—and its board—to shrink
NINE years ago, in the autumn of 2008, the Federal Reserve was fighting a financial collapse. To stave off disaster, it lent aggressively—to banks, to money-market funds, even to other central banks. As a result, its balance-sheet ballooned. At the start of September 2008, the month when Lehman Brothers collapsed, the Fed’s assets totalled $905bn (at the time, about 6% of GDP). By December they had more than doubled in size, to $2.1trn. That was only the start. As its emergency lending unwound, the Fed began purchasing government debt and mortgage-backed securities (MBSs), in an attempt to support the real economy. Three volleys of so-called “quantitative easing” (QE) eventually swelled the balance-sheet to $4.5trn by 2015.
On September 20th the Fed will probably announce that it is putting QE into reverse. It does not intend to sell its assets. Rather, as its securities mature, it will stop reinvesting all of the proceeds. The permitted monthly “run-off” will gradually rise…Continue reading
Stanley Fischer and the twilight of technocracy
IN 2004 Stanley Fischer described the wonder he felt as an economics student in the 1960s. “You had a set of equations”, he said, “that meant you could control the economy.” Technocracy—the dream of scientific government by a caste of wise men—arose in the 20th century, as rapid change rendered the world unfathomably complex; in economics, it came of age in the Keynesian revolution of the 1930s. On September 6th, after a remarkably distinguished career in public service, Mr Fischer, an intellectual heir to Keynes, announced his imminent retirement as the vice-chairman of the Federal Reserve. It is tempting to see in his departure the end of the era and the ideal of technocracy.
A century ago, as physicists unlocked the secrets of the atom and biochemists probed the molecular basis of life, economists sought to systematise their own field. But the growing complexity of their work created a problem: laymen could not make head or tail of it. Government consultation with experts,…Continue reading
Initial Coin Offering means investor caution obligatory

HERE is the deal. You can buy an entry in a computer ledger issued by a startup company on the basis of an unregulated prospectus. It is called an “initial coin offering” or ICO. But though the ledger entry is called a coin, you cannot spend it in any shop. And whereas the use of the term ICO makes it sound like an IPO (initial public offering), the process whereby a firm lists on a stockmarket, coin ownership does not necessarily get you equity in the company concerned.
This sounds like the kind of bargain that would appeal only to people who reply to e-mails from Nigerian princes offering to transfer millions to their accounts. But ICOs may well be the most popular investment craze since the dotcom boom of 1999-2000; even Paris Hilton, a celebrity heiress, has jumped on the bandwagon. The list of active, upcoming and recent ICOs on the website “ICO alert” covers 31 pages of A4 paper and includes around 600 companies. More than $2bn has been raised in total.
There is…Continue reading
ICO stands for Investor Caution Obligatory

HERE is the deal. You can buy an entry in a computer ledger issued by a startup company on the basis of an unregulated prospectus. It is called an “initial coin offering” or ICO. But though the ledger entry is called a coin, you cannot spend it in any shop. And whereas the use of the term ICO makes it sound like an IPO (initial public offering), the process whereby a firm lists on a stockmarket, coin ownership does not necessarily get you equity in the company concerned.
This sounds like the kind of bargain that would appeal only to people who reply to e-mails from Nigerian princes offering to transfer millions to their accounts. But ICOs may well be the most popular investment craze since the dotcom boom of 1999-2000; even Paris Hilton, a celebrity heiress, has jumped on the bandwagon. The list of active, upcoming and recent ICOs on the website “ICO alert” covers 31 pages of A4 paper and includes around 600 companies. More than $2bn has been raised in…Continue reading
A year on, Wells Fargo cannot shake off its mis-selling scandal
ON SEPTEMBER 8th 2016, Wells Fargo’s reputation plummeted abruptly from that of America’s finest bank to that of yet another dodgy company. It was revealed to have opened an enormous number of potentially unauthorised retail deposit, current (checking) and credit-card accounts. A year on, two questions have yet to be put to rest. How much harm did Wells do to its customers? And how much did the scandal hurt the bank itself?
Wells has not been passive in its response. It has produced report after report on its misdeeds and submitted to investigations by two federal regulators, the Consumer Financial Protection Bureau and the Office of the Comptroller of the Currency. It has purged its chief executive and the head of its retail bank, clawed back executive bonuses, transformed its board and simplified its formerly decentralised structure. It has created a comprehensive process for restitution and settled a class-action suit.
Yet it cannot put the scandal behind it. In July it…Continue reading
Hurricane Harvey has exposed the inadequacy of flood insurance
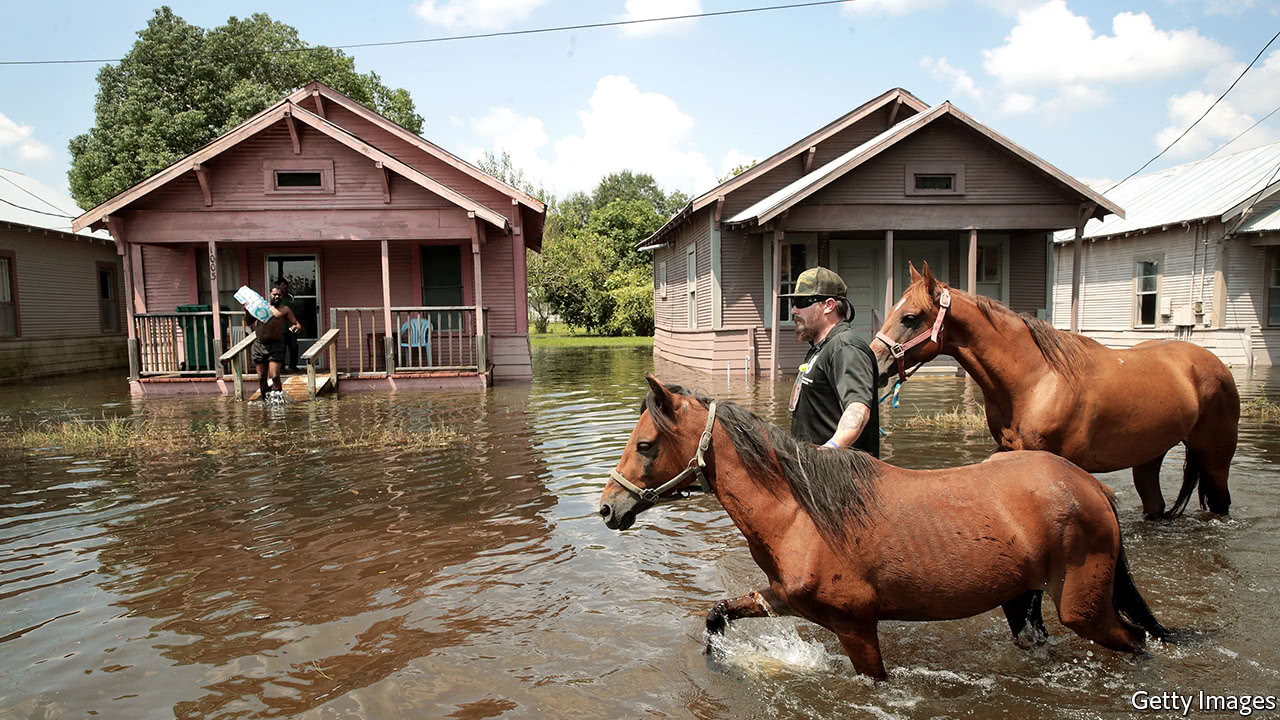
THOSE who live on America’s coasts know to prepare for wrathful hurricanes in late summer—nailing plywood to their windows as the storm approaches. America’s property insurers and reinsurers are ready, too, using sophisticated models to track storms and estimate potential losses. But wind is not the only danger from hurricanes. Ask Houstonians who saw their homes inundated by Hurricane Harvey’s 52 inches (132cm) of rain in the six days to August 30th. Or those in tthe path of Hurricane Irma, which, as The Economist went to press, was wreaking havoc across the Caribbean. But whereas wind damage is covered under most standard insurance policies in America, flood insurance is a government-run add-on that far from all homeowners buy. As a result, of over $30bn in property losses in Texas, only 40% may be insured.
The National Flood Insurance Program (NFIP) was set up in 1968, after a series of large losses led private insurers to pull back. Those living within a…Continue reading
Exchange-rate shifts have helped the global economy

STICKLERS for value have plenty of reasons to frown at financial markets. Much feels out of whack, from squashed bond yields to pricey stockmarkets. Yet currency markets, at least, seem to have shifted in line with fundamentals this year. Take the euro, for instance. Since the start of 2017 it has risen by almost 15% against the dollar, to $1.19 (see chart). That has taken it much closer to fair value by benchmarks such as purchasing-power parity (PPP), the exchange rate at which a basket of goods is worth the same in different countries. The OECD puts the euro’s PPP at $1.33. That is quite a stretch from $1.04 in January. “The elastic had to snap back,” says Kit Juckes of Société Générale, a French bank.
Of course, the euro’s revival is a result of more than its being cheap. The anxiety that elections in Europe might bring to power anti-euro populists, such as Marine Le Pen in France, has dissipated. The euro-zone economy has further strengthened, raising the prospect that monetary…Continue reading
Governments need to rethink their attitudes to debt
GOVERNMENTS do not always make the best budget managers. Assuming it avoids an accidental debt default, America will run a bigger budget deficit this year than the last, despite a booming economy. Germany runs a surplus—but scrimps on critical investments and annoys its euro-area neighbours in the process. Japan, cowering under a mammoth public-debt pile, is weighing raising its consumption tax, though the last rise strangled a tenuous economic recovery. It is awkward, therefore, that the role of fiscal policy as a recession-fighting tool is only growing. The next downturn will be a painful and dangerous learning experience for many politicians.
When that comes, at some point in the next few years, the initial policy response is easily foreseeable. Central banks, nimbler than parliaments, will again move first. But markets reckon that two years from now the Fed’s benchmark rate will remain below 2%, the Bank of England’s below 1% and the European Central Bank’s close to zero. Rates can only go so negative before people abandon the banking system for cash. So cuts to interest rates will be limited. By contrast, in the relatively mild recession of 2001 the Fed cut rates by more than six percentage points. Central-bank asset purchases will follow, assuming they are not already happening, as they might well still be in Europe and Japan. Their effects will be less…Continue reading