
Tag: Finance and economics
A new bond taps private money for aid projects in war zones
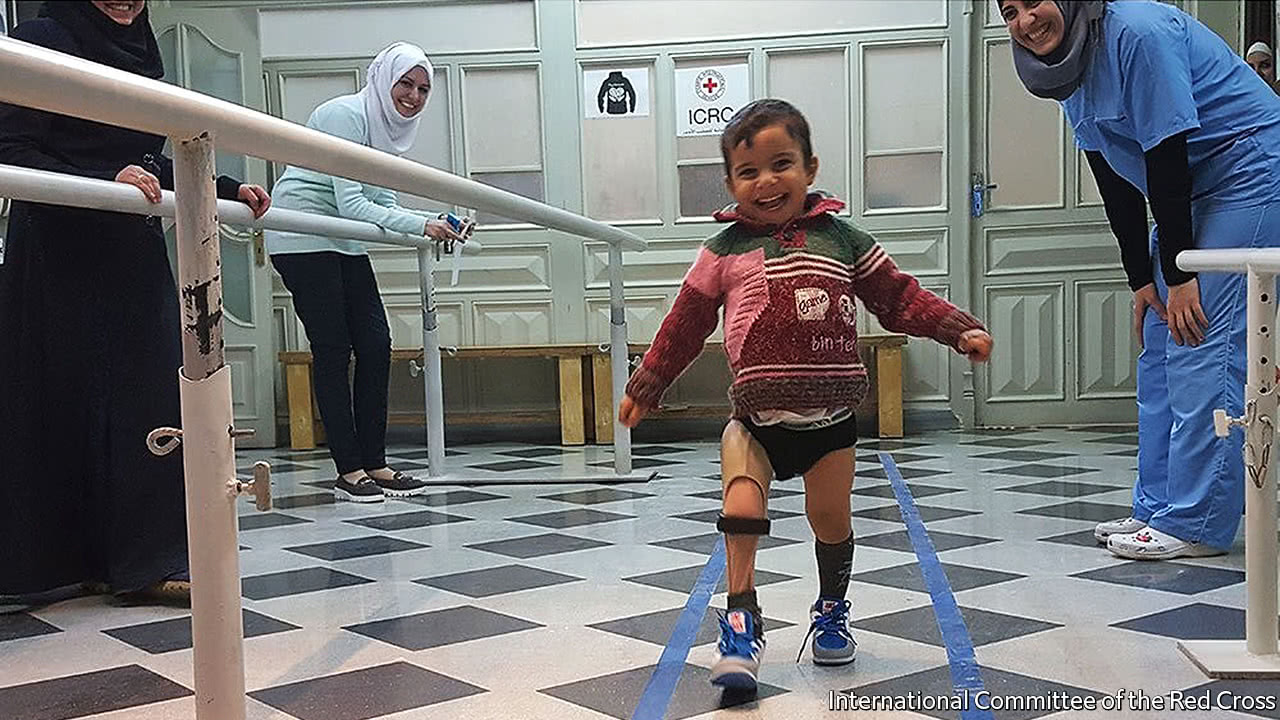
INVESTORS might be expected to run a mile from a deal on offer in a conflict-torn part of Africa. At best, it will pay an annual return of 7%; at worst, 40% of the original investment is lost. But a dozen social investors have pooled SFr26m ($27m) to finance the world’s first “humanitarian impact bond”, issued by the International Committee of the Red Cross (ICRC). It will pay for three rehabilitation centres to be built and run in the Democratic Republic of Congo, Mali and Nigeria.
The ICRC’s obligations are backed by “outcome funders”, ie, donors, mostly governments. The bond is an example of “impact investing”, in which private investors seek out social and financial returns, and of “blended finance”, in which public funds help them to do so. Variants have included a bond aimed at educating girls in India and a World Bank-led initiative to raise money to respond to pandemics. The novelty in the ICRC’s…Continue reading
Why are investors so relaxed about the tensions in Korea?
A ROGUE state has tested what may be a hydrogen bomb and has sent a missile over the territory of a neighbouring country. The American president has promised “fire and fury” if threats continue. The Security Council of the United Nations has been locked in debate. This sounds like the plot of a Hollywood thriller or a paperback potboiler in which the world is heading for conflagration.
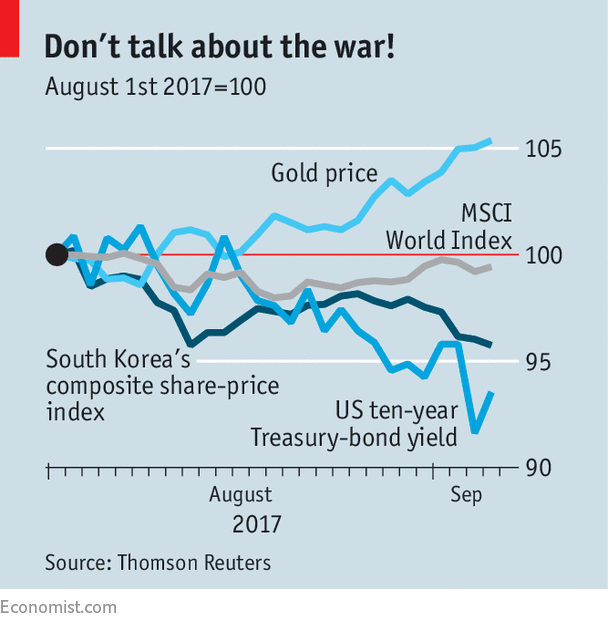
But international investors are not thrilled, and seem barely disconcerted, by the crisis on the Korean peninsula. Gold has risen a bit, the yield on Treasury bonds has dropped and the MSCI World equity index has fallen since the start of August. However, the moves have not been huge. Even the South Korean stockmarket, surely the most sensitive gauge of war risk, is well above its level at the start of the year.
What explains this remarkable insouciance? One possibility is that the markets may simply not be very good at assessing political risk. After all, investors failed to foresee either the…Continue reading
Capacity cuts in China fuel a commodity rally and a debate

STEEL ran in Zhang Cheng’s family for three generations. His grandfather mined iron ore. His father got a job in the big state-owned steel mill just outside Jinan, capital of Shandong province. His mother worked in the on-site hospital. And Mr Zhang went to the mill-run school, graduating to a job in its foundry, where, in the heat of the blast furnace, he rolled metal into thin bars for construction. But after nearly two decades in Jinan Steel, he worked his last day there this summer. In the name of “capacity reduction”—a government policy to rein in excess production of steel—the plant stopped operating in July, and Mr Zhang went on the dole.
Since they worked for a state-owned company, the local government has helped him and the 20,000 others who lost jobs find new ones. But it has been a struggle for Mr Zhang, a soft-spoken man. Openings in Jinan are mainly in the service industry—as a waiter in restaurants or an attendant at a station on the new underground. He worries…Continue reading
A survey finds support for both globalisation and import tariffs

IN JANUARY 2000, George W. Bush, then a presidential candidate, said: “If the terriers and bariffs are torn down, this economy will grow.” His eloquence did little for the cause of free trade. Tariffs have consistently retained broad global support despite the spoonerism.
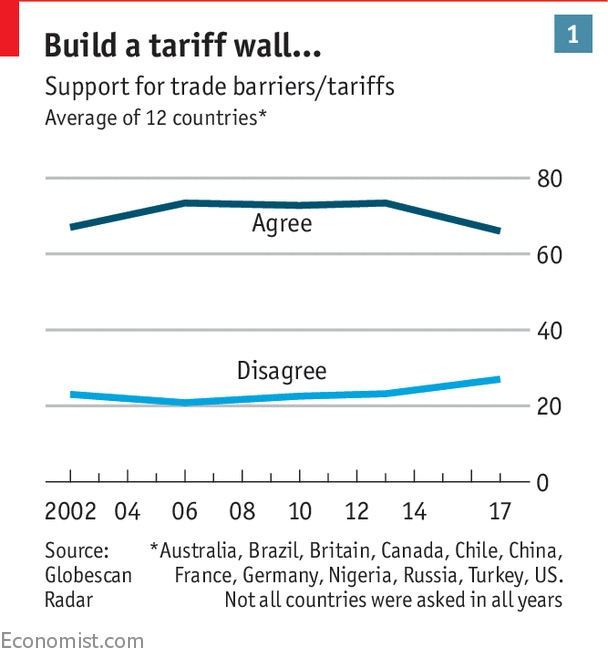
GlobeScan, a consultancy, has regularly conducted surveys in several developing and developed countries. They measure support for trade barriers, globalisation and free markets. Since 2002, average global support for trade barriers has remained relatively stable at around two-thirds of respondents (see chart 1). Support for globalisation and the free market has been…Continue reading
Of Indian banknotes cancelled last year, 99% are accounted for
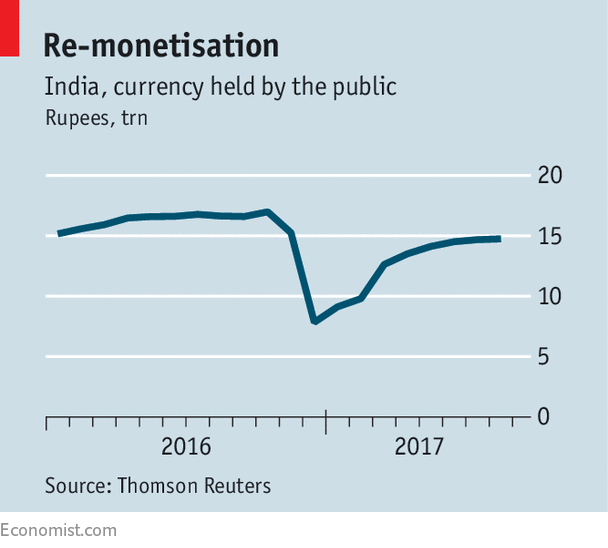
ON NOVEMBER 8th 2016, Narendra Modi, India’s prime minister, stunned its 1.3bn people by announcing that most banknotes would soon become worthless. Indians then queued for weeks on end to exchange or deposit their banned money at banks. The comfort for the poor was that the greedy, tax-dodging rich would suffer more, as they struggled to launder their suitcases full of cash by year-end.
Not so. A report from the central bank, the Reserve Bank of India (RBI), on August 30th suggests that of the 15.4trn rupees ($241bn) withdrawn—roughly 86% of all banknotes by value—15.3trn rupees, or 99% of them, have been accounted for. Either the “black money” never existed or, more likely, the hoarders found a way of making it legitimate.
Defenders of the scheme say it is merely one plank of a wider fight against informal economic activity and corruption. Banks have enjoyed an influx of cash. Digital payments are up (from a low base), as issuance of replacement notes has not caught…Continue reading
Foreign jurisdictions try to lure legal business from London
LOFTILY as they may disdain the profit motive, Britain’s judges are, on a national level, money-spinners. English law is often specified as the one under which commercial contracts are to be interpreted and enforced. And disputes often end up being heard in British courts. But, like any business, the law is competitive, and other jurisdictions want to snatch a share of this market. London is mounting its defences.
It has several hard-to-beat advantages: the use of English; a reputation for fairness; the centuries of precedent that lend predictability. Richard Caird, a partner at Dentons, a global law firm, notes that a foreign company can expect an impartial decision in an English court, even if it is pitted against a British firm. Over 70% of cases in the English commercial courts involve a foreign party. In 2015, Britain had a £3.4bn ($5.2bn) positive balance of payments on legal services.
One way for other financial centres,…Continue reading
Russia’s largest private bank is rescued by the central bank

VADIM BELYAEV’S start in business in the mid-1980s was to sell foreign watches on the black market in the Soviet Union. He became a financier, and by 2015 had transformed his bank, Otkritie, into post-Soviet Russia’s largest private lender. Named “Businessman of the Year” by a Russian magazine, he used an English term to describe himself: “Risk-taker”. The risks have caught up with Otkritie. A run on its deposits led this week to its takeover by the central bank (CBR). The rescue is likely to be the largest in modern Russian history.
Russian banking has been plagued by lenders with bad loans and inadequate capital, and “pocket” banks that function as money-laundering hubs for influential businessmen. The CBR has embarked on a campaign to clean up the sector, taking on formerly untouchable banks with powerful shareholders and clients. Since 2013 it has shut down more than 300 banks.
Otkritie rose rapidly, out of a small predecessor bank acquired in 2006. It has…Continue reading
On NAFTA, Donald Trump’s most dangerous opponents are at home

EVER game for a fight, President Donald Trump is picking one again with Canada and Mexico, America’s partners in the North American Free-Trade Agreement (NAFTA). On August 27th he tweeted that both were being “very difficult”, adding: “May have to terminate?” His strategy, of getting a better deal by threatening to pull out altogether, is odd. It worsens relations with America’s negotiating partners, at a time when Mr Trump’s plans face just as much opposition at home.
Before April American business was quietly hoping that a Trump presidency would lead to more tax cuts than trade tensions. That changed when news leaked that Mr Trump was poised to withdraw from NAFTA. Suddenly the deal had louder champions in American business, including the energy and technology industries.
Knowing this, Canada and Mexico seem unruffled by Mr Trump’s latest threats as they go into the second round of NAFTA renegotiations on September 1st. Earlier ones prompted panicky phone…Continue reading
Analysts struggle to make accurate long-term market forecasts

WHAT is the right way to invest for the long term? Too many people rely on past performance, picking fund managers with a “hot” reputation or backing those asset classes that have recently done well. Just as fund managers cannot be relied on to be consistent, returns from asset classes are highly variable. The higher the initial valuation of the asset, the lower the future returns are likely to be.
That is pretty clear with government bonds. Anyone buying a bond with a yield of 2% and holding it until maturity can expect, at best, that level of return (before inflation) and no more. (There is a small chance the government might default.) With equities, the calculations are not quite so hard-and-fast. Nevertheless, it is a good rule-of-thumb that buying shares with a low dividend yield, or on a high multiple of profits, is likely to lead to lower-than-normal returns.
So a sensible approach to long-term investing would assess the potential returns from asset classes, given their…Continue reading
Market concentration can benefit consumers, but needs scrutiny

WHEN Amazon announced in June that it would buy Whole Foods, an upmarket grocer, for $13.7bn, other firms shuddered. The spread of Amazonian tentacles is worrying to those wary of concentrated corporate power. But shoppers entering their local Whole Foods these days find oddly low prices alongside the new stacks of Echoes, Amazon’s voice-activated digital helpmate. This raises a question. Is Amazon hellbent on building a world-straddling monopoly, or merely injecting innovation and competition into yet another new market? For antitrust regulators, the welfare of the consumer is the priority. Yet working out how to protect it is harder than ever.
Competitiveness in most industries is a matter of degree. In the idealised marketplace of economics textbooks, the price people pay for goods equals the cost of producing an additional unit. Any higher, the theory goes, a competitor could cut the price a smidgen, sell another unit and profit. Yet outside commodity markets, most firms can charge…Continue reading