
Noticias
El beneficio de Abanca creció hasta los 267 millones por un mejor control del gasto
Abanca obtuvo un beneficio neto de 267 millones de euros en los nueves primeros meses del año, un 0,4 % más que en el mismo periodo de 2015, ha informado la entidad en un comunicado. Leer
España quiere devolver otros 1.000 millones del rescate bancario el 11 de noviembre
La operación debe recibir el visto bueno de los socios de la eurozona. Leer
Sabadell logrará un resultado de 625 millones hasta septiembre, según los expertos
La integración del británico TSB, culminada en junio de 2015, condiciona la comparativa frente al pasado ejercicio. Leer
Popular ganará 94 millones con mayor esfuerzo en provisiones, según los analistas
Apenas generará beneficio, teniendo en cuenta las pérdidas esperadas pendientes de reconocer en el último trimestre. Leer
Los analistas prevén que el beneficio de CaixaBank alcance 897 millones, un 10% menos
Contabilizará gastos de explotación extraordinarios por 125 millones ligados al plan de bajas voluntarias que va a poner en marcha. Leer
Jail bait

ONE thing right-wing populists and left-wing progressives can agree on is that society is too soft on white-collar crime. Conservatives abandon their admiration for business when it comes to “crooked bankers”. Left-wingers forget their qualms if locking up “corporate evil-doers”. Hillary Clinton’s line that “there should be no bank too big to fail but no individual too big to jail” would go down equally well at a Donald Trump rally.
But is society really soft on corporate wrongdoing? And would locking up bankers and businessmen and throwing away the key really solve any problems? Two new books try to inject reason and evidence into a discussion more commonly driven by emotion and hearsay: “Why They Do It: Inside the Mind of the White Collar Criminal” by Eugene Soltes, of Harvard Business School, and “Capital Offenses: Business Crime and Punishment in America’s Corporate Age” by Samuel Buell, the lead prosecutor in the Enron case, who now teaches at Duke University.
Messrs Soltes and Buell both demonstrate that America is getting tougher on business crime. Between 2002 and 2007 federal prosecutors convicted more than 200…Continue reading
Big tobacco’s new ambitions
 Innovator at work
BIG Tobacco is about to get even bigger. On October 21st British American Tobacco (BAT) announced that it had bid $47bn for the 58% of Reynolds American that it does not already own. Though Brexit has weighed on some British companies, BAT is unencumbered, with most of its revenue earned overseas. Many investors expect the deal to go ahead, although BAT might need to puff up its offer. BAT would then become the world’s largest tobacco company by sales and profits.
As in other volume businesses, like beer, some of the merger logic is simply to cut costs. With consolidation, BAT reckons its deal would generate $400m of annual savings. However, it also underscores two big, long-term changes for cigarette-makers.
The first is that America has become an attractive market for tobacco firms and buying Reynolds, whose brands include Camel and Newport, is the easiest way for BAT to grow there. This is a reversal from the recent past. Not long ago America seemed stale and overrun by lawsuits, particularly compared with fast-growing economies. Cigarette firms quarantined their American businesses. In 2004…Continue reading
How to confront a dark corporate past
“WE THOUGHT we knew our story, and we knew it wasn’t great,” says Maurice Brenninkmeijer, chairman of COFRA Holding, which owns C&A, a 175-year-old Dutch clothing retailer with over 2,000 stores globally. Yet the full account of how the German branch of his family behaved in the second world war “tore through your heart when you heard it”, he adds. Mr Brenninkmeijer’s ancestors—considered to be genial, virtuous, Catholic and reserved—turned out to have been avid Nazi collaborators. Old letters revealed cosy, corrupt, ties to Hermann Goering. From 1942 onwards C&A and Siemens, a German engineering firm, together exploited forced Eastern European labourers in Germany, keeping them in such a wretched state that malnutrition killed several women and children. C&A profited from “Aryanisation”, grabbing business and property from terrified Jewish owners. Perhaps worst, it used Jewish tailors and leather-workers, corralled in Lodz, a dreadful ghetto in Poland. Of some 200,000 people trapped in inhumane conditions there, only 1,000 survived to liberation.
Such grim details are now public thanks to Mark Spoerer, a historian in Regensburg who specialises in archival research to assess companies’ dark pasts, putting “immoral business behaviour” into historical context. Remarkably, his new book “C&A: A family business in Germany, the…Continue reading
The greatest moderation

ON OCTOBER 19th China reported that its economy grew by 6.7% in the third quarter. It would have been an unsurprising, reassuring headline, except that China had reported exactly the same figure for the previous quarter—and for the quarter before that. This freakish consistency invited the scorn of China’s many “data doubters”, who have long argued that it fudges its figures. China has expanded at the same pace from one quarter to the next on numerous occasions. But it has never before claimed to grow at exactly the same rate for three quarters in a row.
Has anywhere? This growth “three-peat” is not entirely without precedent. Seven other countries have reported the same growth rate for three quarters in a row, according to a database spanning 83 countries since 1993, compiled by the Economist Intelligence Unit, our sister company. The list includes emerging economies like Brazil, Croatia, Indonesia, Malaysia and Vietnam, but also two mature economies: Austria and Spain. Indeed, Spain has performed this miracle of consistency twice. It grew by 3.1% (year-on-year) in the first three quarters of 2003 and by 4.2% in the first…Continue reading
Brazilian firms emerge from the gloom
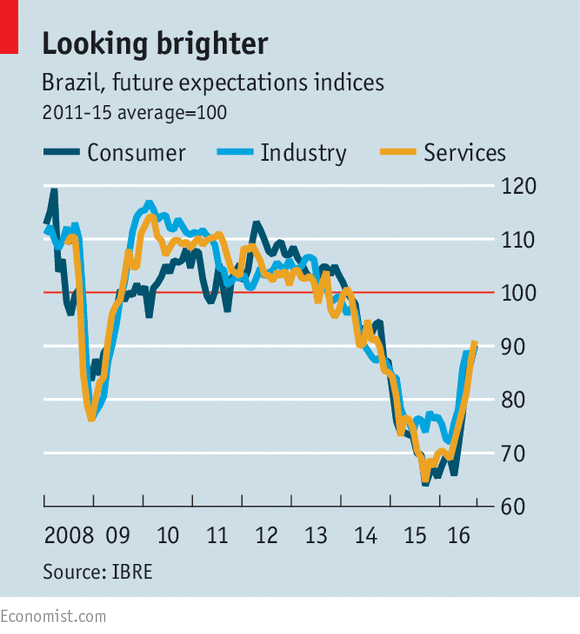
“BRAZIL is back in business,” proclaimed Abílio Diniz, chairman of BRF, a Brazilian pork and poultry giant, at a recent investor shindig. Really? The economy, mired in recession since mid-2014, is not expected to stir before the end of the year—and then only sluggishly. After rebounding in the first half of 2016, industrial production plummeted again in August. Retail sales fell by more than forecast. Firms expect to hire just 100,000 temporary workers in the run-up to Christmas, 3% fewer than last year’s already low tally. BRF’s own domestic operations are hardly a picture of health. Sales dropped by 5% in the second quarter, year on year (though this was offset by rising global revenues).
For all that, Mr Diniz is not alone in his optimism. Surveys point to rising confidence among bosses and consumers alike (see chart). Investors’ spirits are up—and with them the São Paulo stockmarket, which has returned to levels last seen in 2012. The real has strengthened by a third against the dollar since January.
The collective mood swing has less to do with the real economy, and more with realpolitik. In August the…Continue reading