
Tag: Finance and economics
Who will be the next chair of the Federal Reserve?
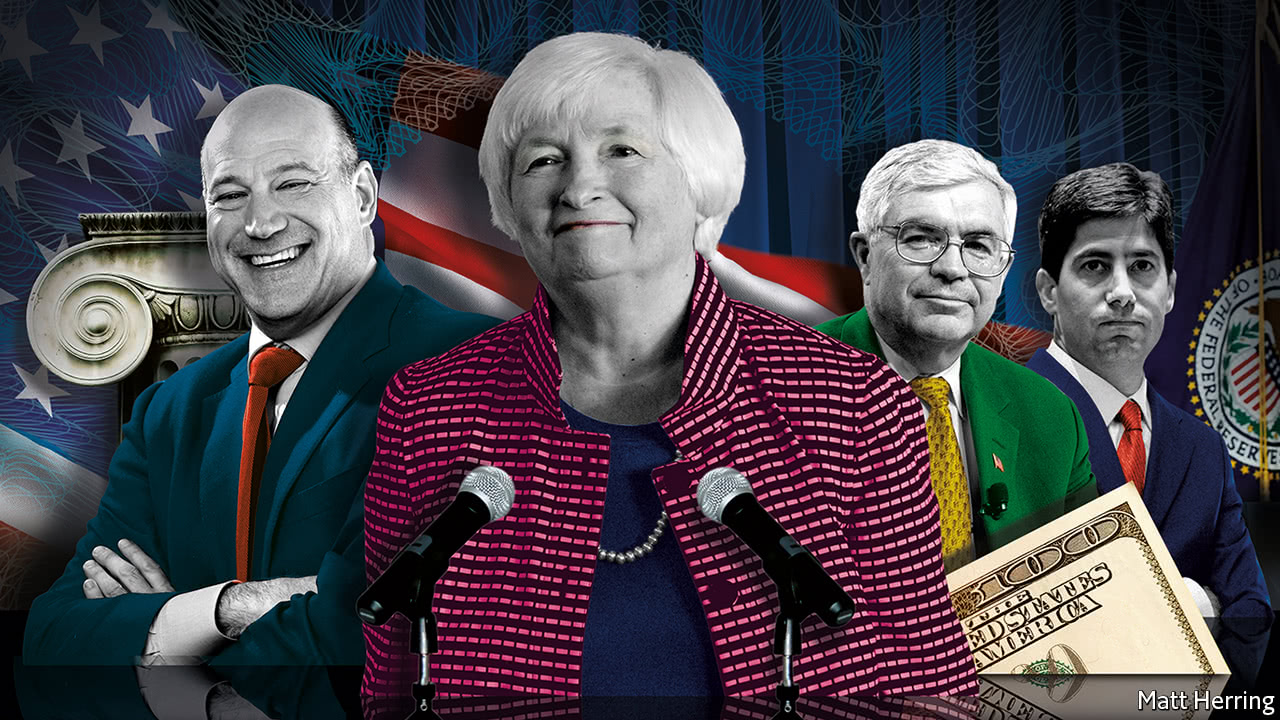
LOOK only at unemployment and inflation, says Peter Conti-Brown, a historian of the Federal Reserve, and Janet Yellen is the Fed’s most successful boss of all time. The second indicator may be below target, but that is a blip compared with the recessions most Fed chairmen have endured. So it is perhaps not surprising that President Donald Trump is openly considering retaining Ms Yellen, a Democrat installed by Barack Obama, after her term ends in February 2018. Nor by historical standards is it odd: the Fed’s past three leaders were all reappointed by presidents from the other party. Yet Ms Yellen, whom Mr Trump criticised on the campaign trail, is not the leading candidate. PredictIt, a betting site, gives her a 28% chance of staying put. In front of her, with a 36% chance of appointment, is someone else Mr Trump is publicly weighing up: Gary Cohn (on the left above).
Mr Cohn was until January the chief operating officer and president of Goldman Sachs. He left that role to become the…Continue reading
Research points to a new explanation of “Dutch disease”
IN 1959 geologists discovered 2.8trn cubic metres of natural gas—the largest field in Europe—under the city of Groningen in the Netherlands. Cheap gas and free-spending energy firms were thought to be good news for the entire Dutch economy. But higher gas-export prices in the 1970s raised the value of the guilder by a sixth, hitting the competitiveness of Dutch manufacturing and services. In 1977 The Economist dubbed this economic curse “Dutch disease”.
Other resource-rich countries have tried to avoid this trap. Some have adopted fixed exchange rates to prevent their currencies appreciating. Others save capital inflows in sovereign-wealth funds to avoid distorting their economies. Yet many still have underdeveloped non-commodity sectors. And despite having plenty of cash to invest, banks are particularly affected.
Two recent IMF papers point to a new explanation of why commodity exporters have such stunted banks. The problem, they…Continue reading
A crucial interest-rate benchmark faces a murky future

EVERY working day, shortly before noon, British time, the London Interbank Offered Rate, or LIBOR, is published. For five currencies and seven maturities, from overnight to 12 months, it is the average, trimmed of outliers, of up to 20 banks’ estimates of the interest rate at which they can borrow from other banks. It is also the benchmark for financial contracts reckoned to be worth $350trn. Derivatives depend on it most. But plenty of asset-management products, as well as corporate loans and mortgages, are based on LIBOR and similar rates, notably EURIBOR, an interbank rate for euros.
Yet LIBOR’s days may be numbered. Regulators are promoting other benchmarks. On July 27th Andrew Bailey, the head of Britain’s Financial Conduct Authority, said that the FCA had spoken to banks about sustaining LIBOR until the end of 2021, but no longer. In April a working group set up by the Bank of England concluded that SONIA (the Sterling Overnight Interbank Average Rate), which the central bank…Continue reading
The private-equity business learns to be more flexible
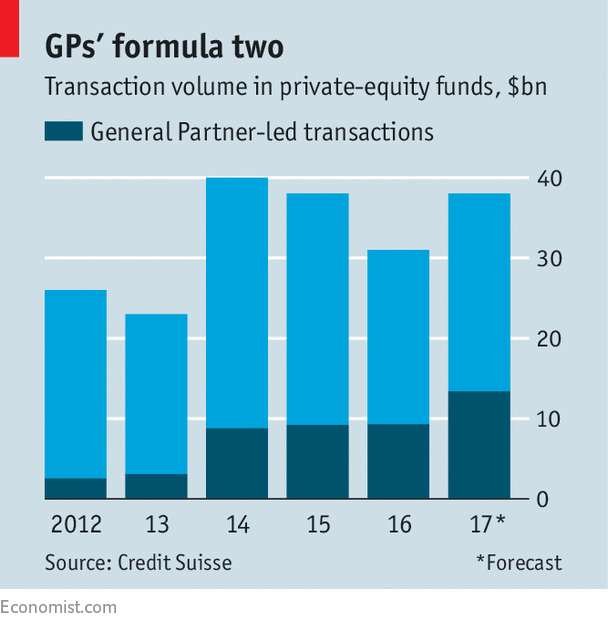
THE private-equity business presents a paradox. Its barons like to boast of revamping the companies they buy. But they themselves have been steadfast to their own business model, centred on funds with a ten-year life. Within this time span, fund managers, known as “general partners” (GPs), commit to buy, manage and sell a clutch of companies; investors commit to lock up their money for the duration. Sometimes GPs or investors chafe at the time constraint. A new segment of the secondary market, “GP-led” deals, has sprung up to help them.
Investors wanting to exit a fund early need to find a buyer for their stake in the secondary market. But sometimes none will offer an attractive price. Sometimes also, a fund nearing its expiry date may find itself still holding a large number of its investments. GP-led deals place the onus on fund managers to find buyers.
Such transactions have quickly grown from just 10% of the secondary market in 2012 to over one-third this year, according…Continue reading
Genetic testing threatens the insurance industry
IF A genetic test could tell whether you are at increased risk of getting cancer or Alzheimer’s, would you take it? As such tests become more accessible, more and more people are saying “yes”. The insurance industry faces a few headaches as a result.
Once used only for medical reasons, basic predictive genetic tests can now be ordered online for a few hundred dollars. One company, 23andMe, in California, has collected some 4,000 litres of sputum since 2007, enlightening 2m people on their ancestry, health risks and what they may pass on to offspring. In April it received regulatory approval to screen for risk factors connected to ten diseases and genetic conditions, including late-onset Alzheimer’s and Parkinson’s. The ruling could open the floodgates for others to sell direct to consumers.
“Information is power”, argue many who take such tests. But insurers fear that without equal access to such information, they…Continue reading
Why national accounts might be like corporate balance-sheets
THE easiest way to get an economist to laugh sardonically is to compare a country’s finances to those of a family. It is both simplistic and wrong, they will argue, for politicians to say that a country “must live within its means”.
But in a new working paper* from the National Bureau of Economic Research, Patrick Bolton and Haizhou Huang make a different comparison; between the finances of a government and those of a company. A business can finance itself in three ways: through internal funds (its revenues); through borrowing; and through equity (the issuance of new shares). In the first two cases, it is easy to see the analogy with a nation state; governments can raise money from taxes or borrow in the form of government bonds.
But the paper’s most striking idea is that the national equivalent of equity is fiat money. Governments are able to issue money that can be used to settle debts and pay taxes—the term “fiat” comes from the Latin for “let it be done”….Continue reading
How crisis-hit economies become investment darlings
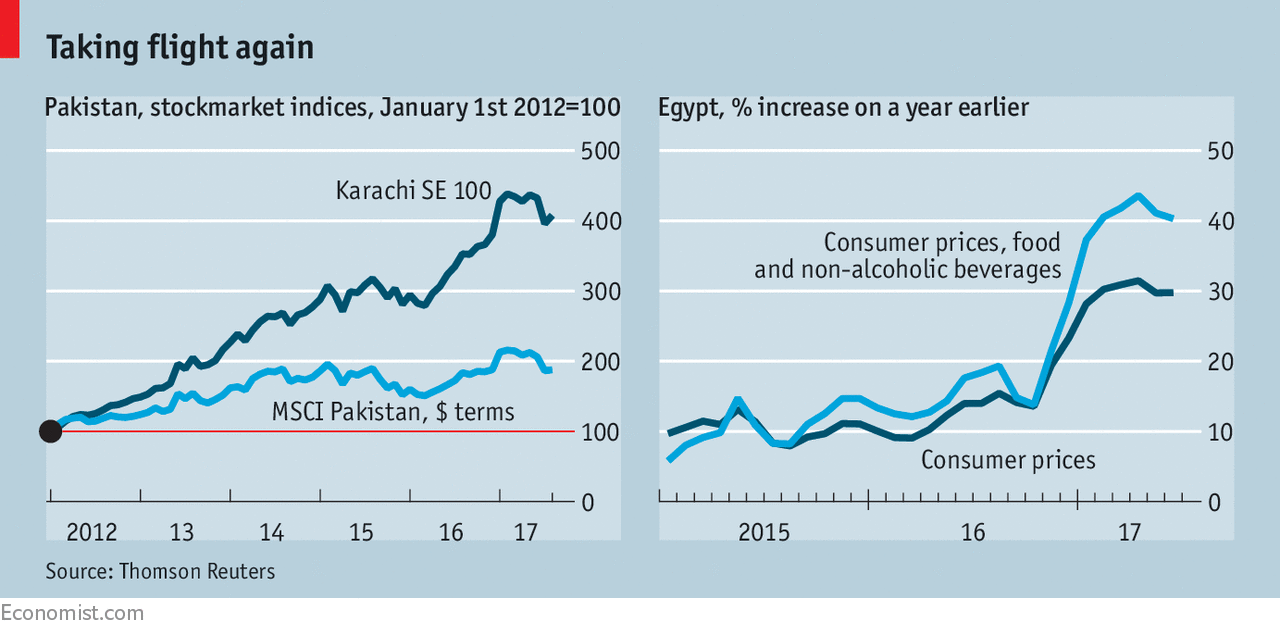
NAWAZ SHARIF is the ex-prime minister of Pakistan again. His third stint in the job ended on July 28th after the Supreme Court disqualified him from office. Yet he could justifiably claim that he left Pakistan’s economy in a better state than he found it. When Pakistan last went to the polls, GDP had been growing at around 3%, a dismal rate for a poor country with a burgeoning population. Inflation was above 10%. The budget deficit had ballooned. A crisis loomed. Four years on, inflation is in the low single digits. The budget deficit has shrunk to a little above 4% of GDP. The GDP growth rate is closing in on 6%. Investors too have taken notice. Since 2012, Pakistan’s stockmarket capitalisation has doubled in dollar terms (see chart).
Bitcoin divides to rule
COMPARED with Brexit, Bitexit seems a piece of cake. On August 1st, without much agonising or awkward negotiation, a group of Bitcoin activists and entrepreneurs managed to create a second version of the crypto-currency. It immediately gained a following: in less than a day of existence, the value of a unit of “Bitcoin Cash” jumped to over $600, and tokens worth more than $10bn were in circulation (although that is still much smaller than Bitcoin classic, which stood at about $2,700 and nearly $45bn).
This “fork”, as such events are called, came earlier than foreseen. But it is broadly how insiders had expected a two-year-old conflict over the future of Bitcoin to end. At the heart of this “civil war” was the question of how to increase the capacity of the system, which can only handle up to seven transactions per second. The new version is able to process 56 per second, but otherwise works much like the original one.
Will Bitcoin Cash be more than just another “altcoin”, as the many existing clones of the crypto-currency are called? It is backed by Chinese “miners”, firms that provide the computing power to confirm payments and mint new digital coins. They have been unhappy with how the original system has been managed by its developers—and made some further technical tweaks to ensure that the new Bitcoin survives. The followers of…Continue reading
Tech stocks have regained their dotcom-era highs
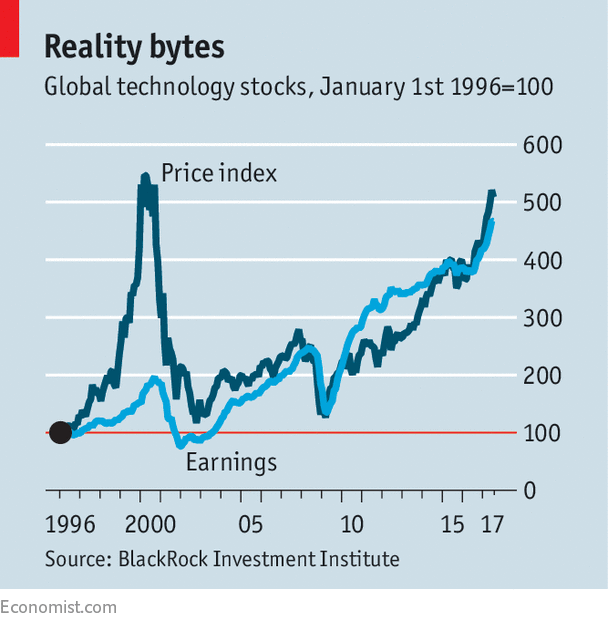
CAST your mind back to when Bill Clinton was president, Tony Blair and Vladimir Putin were fresh-faced new leaders and tweeting was strictly for the birds. That was when technology stocks, as measured by the S&P 500 tech index, last traded at their current levels.
The horrendous decline in share prices that followed the peak in 2000 was the first financial calamity of this millennium. The dotcom crash had much less impact on the broader economy than the mortgage and banking crisis of 2007-08. Nevertheless, the tech revival has caused some twitchiness among investors. Might history be repeating itself?
In the intervening years the world, and the tech industry, have changed a lot. In the late 1990s enthusiasm for tech shares was so great that the sector’s market value rose far faster than its earnings. The gap is nothing like as great today (see chart). Back then, leading firms like Microsoft and Oracle were valued at more than 20 times their annual revenues, let alone earnings….Continue reading
Making Bitcoin work better

IN DIFFERENT circumstances the two people could be good friends. Each is rather shy and very smart. And each is passionate about bitcoin, a digital currency. One invented hashcash, which foreshadowed components of the crypto-currency; the other is the author of the first Chinese translation of the white paper in which Satoshi Nakamoto, the elusive creator of bitcoin, first described its inner workings.
Adam Back is the chief executive of Blockstream, a British startup, which employs some of the main developers of the software that defines bitcoin’s inner workings. Jihan Wu is the boss of Bitmain, a Chinese firm, which makes about 80% of the chips that power “miners”, specialised computers that keep the bitcoin network secure, confirm payments and mint new digital coins. But far from being fellow-travellers, each represents one of the two main camps in what has come to be called a “bitcoin civil war”, fought over how, if at all, the system should grow.
The worst seems…Continue reading