
Tag: FINANCE
China’s leading economists are in high demand and short supply

EVERGRANDE, a Chinese property firm, is a big spender. It was until recently the country’s most indebted developer. It also owns a football club with one of the highest payrolls in China. It has extended its largesse to a new field: economics. Having founded an economic-research institute, Evergrande last month poached Ren Zeping, a star analyst with a big brokerage, to serve as its first chief economist. His annual salary of 15m yuan ($2.3m) is, based on available information, the highest ever for an economist in China. Not bad for a country where forecasting the official growth figures accurately has for years required little more research than reading the official growth targets.
Yet Evergrande is not alone in splashing cash in China, whether in property, football or, lately, economics. Competition for the best—or, rather, best-known—economists is fierce. The past half year alone has resembled a frenzied transfer window for their services. Besides Mr Ren, half a dozen other…Continue reading
Millennials are doing better than the baby-boomers did at their age
ALL men are created equal, but they do not stay that way for long. That is one message of a report this month by the OECD, a club of 35 mostly rich democracies. Many studies show how income gaps have evolved over time or between countries. The OECD’s report looks instead at how inequality evolves with age.
As people build their careers, or don’t, their incomes tend to diverge. This inequality peaks when a generation reaches its late 50s. But it tends to fall thereafter, as people draw redistributive public pensions and quit the rat race, a contest that tends to give more unto every one that hath. Old age, the OECD notes, is a “leveller”.
Will it remain so? Retirement, after all, flattens incomes not by redistributing from rich seniors to poor, but by transferring money to old people from younger, working taxpayers. There will be fewer of them around in the future for every retired person, reducing the role of redistributive public pensions.
One logical response to the diminishing number of workers per pensioner is to raise the retirement age. But that will exacerbate old-age inequality, if mildly. Longer careers will give richer workers more time to compound their advantages. And when retirement eventually arrives, the poor, who die earlier, will have less time to enjoy their pensions.
Today’s youngsters may resent having to provide…Continue reading
India recapitalises its state-owned banks
ONE of the perks of owning a bank is the ability to tap it when you need money. The Indian government, which has majority stakes in 21 lenders, is no exception. As it happens, it needs to finance a bail-out of the banks it owns, most of which are in trouble. So under a cunning plan unveiled on October 24th, the ailing banks will lend the government 1.35trn rupees ($21bn), about a third of their combined market value. The government will reinvest this money in bank shares, thus ensuring they no longer need a bail-out.
Steadying a tottering financial system is never a graceful exercise, as American and European authorities discovered after the financial crisis. India’s lenders withstood the meltdown of 2007-08 well, but then embarked on an ill-advised lending spree, backing lots of infrastructure projects that got snarled in bureaucracy. Bad loans piled up. State-owned lenders, which account for around two-thirds of the sector, now have…Continue reading
Will corporate tax cuts boost workers’ wages?
THE president’s tax promise has always been clear: he will reduce the amount middle-earners, but not rich Americans, must pay. Yet every time Donald Trump releases a plan, analysts say it does almost the opposite. The Tax Policy Centre, a think-tank, recently filled in the blanks in the latest Republican tax proposals and concluded that more than half of its giveaways would go to the top 1% of earners. Their incomes would rise by an average of $130,000; middle-earners would get just $660. The White House maintains that tax reform will deliver a much heftier boost to workers’ pay packets. Who is right?
The disagreement boils down to who benefits when taxes on corporations fall. The Tax Policy Centre says it is mainly rich investors. But in a report released on October 16th, Mr Trump’s Council of Economic Advisers (CEA) claimed that cutting the corporate-tax rate from 35% to 20%, as Republicans propose, would eventually boost annual wages by a staggering $4,000-9,000 for the average household.
The claim has sparked a debate among economists that is as ill-tempered as it is geeky. Left-leaning economists are incredulous. Writing in the Wall Street Journal, Jason Furman, who led the CEA under Barack Obama, pointed out that if the report is right, wage increases would total about three to six times the cost of the tax cut. Larry…Continue reading
Silicon speculators
EXCHANGE-TRADED funds (ETFs) were supposed to make investing easy. Instead of spending hours researching individual stocks and bonds or paying an expert fund manager, investors could simply buy a few ETFs. But now there are too many to choose from. BlackRock offers 346 in America alone. Some investors need help allocating their money between different funds. Many companies now offer “automated wealth managers” (AWMs) that perform this service.
AWMs have been around for less than ten years, but they have proliferated, offering different services in different countries. Often, they are called “robo-advisers”, but this term can be misleading. Some offer clients detailed advice about how to save. For example, Wealthfront, an American AWM, predicts the cost of sending a student to a given college, taking into account increases in tuition fees and likely financial aid. It then suggests how parents can save in a tax-efficient way. Other…Continue reading
Italy’s fourth-biggest bank returns to the stockmarket
A TELEVISION advertisement for Monte dei Paschi di Siena begins with a toddler tumbling and a gymnast stumbling. “Falling is the first thing we learn,” declares the voice-over. “The second is getting up again.” Italy’s fourth-biggest bank and the world’s oldest, which was bailed out by the Italian government in July, has had several bruising falls over the years. On October 25th it returned to the stockmarket after a ten-month hiatus—the latest stage of its plan to get back on its feet. The shares closed higher on the day, at €4.55 ($5.37), but still far below the €6.49 the government paid.
Trading was suspended last December, after a failed private-sector attempt to save the bank through a share issue. The government said it would get involved. In July the European Commission approved a €8.1bn “precautionary recapitalisation”. European rules say banks receiving such aid must be solvent, the capital injection must not distort competition and the capital…Continue reading
Firms should make more information about salaries public

SWEDES discuss their incomes with a frankness that would horrify Britons or Americans. They have little reason to be coy; in Sweden you can learn a stranger’s salary simply by ringing the tax authorities and asking. Pay transparency can be a potent weapon against persistent inequities. When hackers published e-mails from executives at Sony Pictures, a film studio, the world learned that some of Hollywood’s most bankable female stars earned less than their male co-stars. The revelation has since helped women in the industry drive harder bargains. Yet outside Nordic countries transparency faces fierce resistance. Donald Trump recently cancelled a rule set by Barack Obama requiring large firms to provide more pay data to anti-discrimination regulators. Even those less temperamentally averse to sunlight than Mr Trump balk at what can seem an intrusion into a private matter. That is a shame. Despite the discomfort that transparency can cause, it would be better to publish more…Continue reading
For American Express, competition will only intensify
HE IS leaving with the share price rising and the announcement, on October 18th, of earnings that were largely well received. Better still, Kenneth Chenault, American Express’s chief executive for 16 years, accomplished a feat rare in the upper reaches of American finance: to stand down without an obvious helping shove. No grandstanding senators hounded him out (see Wells Fargo). No boardroom coup hastened the end (Citigroup). The financial crisis left him untouched (take your pick). His successor, Stephen Squeri, promoted from within and apparently groomed for the job, takes over in February.
For all that, Mr Chenault’s long tenure has not been an unequivocal triumph. Though generating strong returns on assets and equity, American Express has continued its slide within the fast-changing and competitive payments industry. According to Nilson, an industry bible, in 1974 the amount of money for purchases channelled through American Express was equivalent to 50% of what went through…Continue reading
Sauce for a Brussels goose
DIVORCES are rarely easy. In the 16 months since Britain voted to leave the EU in a referendum, the negotiations have made little progress. One of the trickiest aspects is the amount that Britain should pay to meet its existing spending commitments for EU programmes.
This is not analogous to dividing up the bill in a restaurant, and deciding who had the lobster and who stuck to the mixed green salad. Take the cost of EU officials’ pensions. The tricky bit in calculating it is that pensions are long-term commitments; a bureaucrat who starts work in Brussels today might still be collecting a pension 70 years from now. Working out the cost is fiendishly complicated, requiring estimates of how much wages will rise (if the pension is linked to salary) and how long employees will live. Then the sum of future benefits has to be discounted at some rate to work out the current cost; the higher the discount rate, the lower the presumed expense.
The EU doesn’t pre-fund pensions for…Continue reading
Multilateral lenders vow openness about their carbon footprints
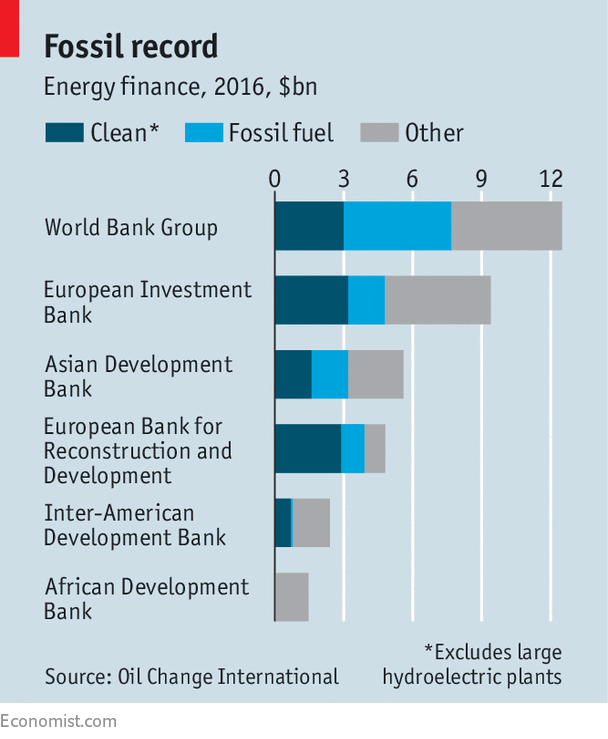
THE World Bank gets a lot of flak. Developing countries clamour for a bigger role in its management. President Donald Trump’s administration lambasts it for lending too much to China. Employees are in open rebellion against their boss, Jim Yong Kim. Now the embattled institution faces criticism from a traditionally friendlier quarter: environmentalists. They accuse it and other multilateral development banks (MDBs) of not being upfront about their true carbon footprint.
That must hurt. After all, MDBs pioneered climate-friendly finance. Ten years ago the European Investment Bank issued the world’s first green bond to bolster renewables and energy-efficiency schemes. The World Bank has not backed a coal-fired plant since 2010. In 2011-16 it and the five big regional lenders in the Americas, Asia, Africa and Europe offered developing countries a total of $158bn to help combat climate change and adapt to its effects. They disclose the amount of carbon dioxide emitted by their day-to-day…Continue reading