
Tag: Business and finance
Donald Trump’s win has sent the shares of small American companies on a tear

THERE have been plenty of swings in financial markets since America’s election on November 8th. The Mexican peso has fallen against the dollar, reflecting worries about Donald Trump’s protectionist tendencies. Ten-year bond prices have tumbled as investors factor in the likelihood of much higher government borrowing. One particularly striking move has been a surge in the share prices of small firms. The Russell 2000 index of American midgets has leapt by 12%, compared with a 3% rise for the S&P 500 index of multinational leviathans (see chart).
Small companies are the backbone of America’s economy, employing about half of the private-sector workforce. But they have had a rotten decade. The Russell index had lagged the stockmarket until the election. The country’s 28m small firms—most of them unlisted—have never fully recovered from the financial crisis of 2008. As of October, confidence had yet to rise back to the level of 2006, according to an index of optimism that is based on surveys by the National Federation of Independent Business, a lobbying group. Giant firms, meanwhile, have been playing a bigger role: two-thirds…Continue reading
Sell-side share analysis is wrong
“SELL-SIDE” analysts, whose firms make money from trading and investment banking, are notoriously bullish. As one joke goes, stock analysts rated Enron as a “can’t miss” until it got into trouble, at which point it was lowered to a “sure thing”. Only when the company filed for bankruptcy did a few bold analysts dare to downgrade it to a “hot buy”.
Economic research shows that there is some truth to the ribbing. The latest figures from FactSet, a financial-data provider, show that 49% of firms in the S&P 500 index of leading companies are currently rated as “buy”, 45% are rated as “hold”, and just 6% are rated as “sell”. In the past year, 30% of S&P 500 companies yielded negative returns.

Profits forecasts made more than a few months ahead have a dismal record of inaccuracy. According to Morgan Stanley, a bank, forecasts for American firms’ total annual earnings per share made in the first half of the year had to be revised down in 34 of the past 40 years. Studying their forecasts over time reveals a predictable pattern (see chart 1).
In theory, a diligent share analyst should do his own…Continue reading
Revising bank-capital standards
A STEEP climb awaited the Basel Committee on Banking Supervision in Santiago on November 28th and 29th. The central bankers and regulators hoped to agree on revisions to Basel 3, the post-crisis version of bank-capital standards. On November 30th Stefan Ingves, the group’s chairman and head of Sweden’s central bank, said that “the contours of an agreement are now clear”. But the climbers are still short of the summit.
The committee had proposed restricting the use of banks’ internal models for calculating risk-weighted assets—which in turn help determine how much capital banks must have at hand. Models varied too much, it said; low risk-weights were flattering some banks’ ratios. But European bankers and officials had complained for months that the proposals would penalise banks that have lots of (low-risk) corporate loans or mortgages (eg, in Germany or Sweden). They sniffed an American plot: American banks, holding fewer such assets, would be untouched.
Mr Ingves gave few details, but said that the new set-up would “largely retain” internal models, though with minimum values for important parameters (such as the probability of default). A “standardised” approach will replace alternatives based on banks’ models for estimating operational risk (big fines, say, or cyber-security breaches).
Not surprisingly, the thorniest topic…Continue reading
Japanese golf courses hunt for a new driver
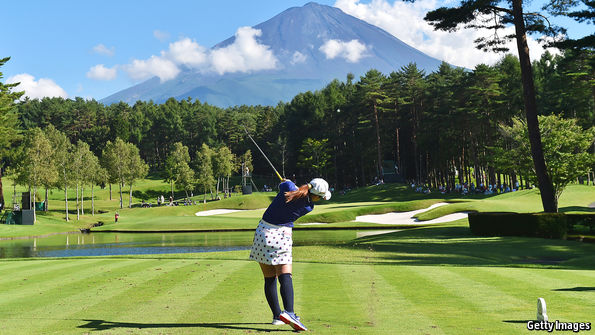 Slow fade
THE gold-coloured golf club priced at $4,700 that Japan’s prime minister, Shinzo Abe, gave to Donald Trump, America’s president-elect, in their first meeting last month may have been a piece of polished diplomacy. But it is unlikely to revive its posh Japanese maker, Honma, which calls itself “golf’s aristocracy”, presumably because it crafts the world’s most expensive clubs. It went bankrupt after Japan’s bubble-era splurge on new golf courses. Seven years ago a businessman from China bought the firm, hoping for an upswing.
Golf, long associated with extravagance in Japan, is flagging. Clubs have trimmed green fees as the level of golf-playing among Japanese has fallen by over 40% since a high in the early 1990s. As elsewhere, courses are in oversupply: Japan has over 2,300—half of Asia’s total.
More than 120 have closed since 2010. Entrepreneurial types have converted about 70 into solar-panel plants, encouraged by state subsidies for alternative-energy production following the disaster in March 2011 at the Fukushima Dai-ichi nuclear-power plant. A few others have been turned back into…Continue reading
The yuan’s weakness is a dilemma for China’s central bank

YUAN forecasters have had it easy for the past decade. But for a few isolated days, China’s currency has been a one-way bet for years on end, whether appreciating against the dollar, pegged to it or, more recently, depreciating. The pace at which it has risen and fallen has also been predictable: the central bank always made it gradual. So Guan Qingyou, of Minsheng Securities, thought himself on solid ground when he predicted in early November that the yuan would stay above 6.82 per dollar for the rest of the year. Less than a week later he was proved wrong: the yuan fell to an eight-year low. Mr Guan published an apology: the art of knowing the yuan’s future with any precision, he conceded, had become rather tricky.
Most analysts, investors and companies believe that the Chinese currency has further to fall against the dollar, but can only guess as to how far and how quickly. Their uncertainty reflects a new reality. The government, long able to exercise tremendous control over the yuan, has started to lose its grip. A new exchange-rate mechanism, introduced last year, has made the currency more flexible but also more responsive to…Continue reading
Regional inequality is a hard problem to solve

THE political shock of Brexit and of the election of Donald Trump have led to new interest in the problem posed by regional inequality. Both shocks drew support from places to which recent economic trends have not been especially kind, and both were reactions, at least in part, against the economic success enjoyed by elites concentrated in a relatively small number of rich metropolitan areas. Even economists, whose «nihilism…about what we can do to help struggling places in the U.S. is, quite frankly, strange» (in the words of Adam Ozimek) have taken to reconsidering their priors on the issue. Myself included; as I noted recently:
The economic literature is pretty clear that moving people from low productivity places to high productivity places is very good for both the people that move and the economy as a whole. It’s also pretty clear that place-based policies designed to rejuvenate regions which have lost their economic reason for being tend not to work very well. And one logical…Continue reading
OPEC reaches a deal to cut production

EXACTLY two years after Saudi Arabia coaxed its fellow OPEC members into letting market forces set the oil price, it has performed a nifty half-pirouette. On November 30th it led members of the oil producers’ cartel in a pledge to remove 1.2m barrels a day (b/d) from global oil production, if non-OPEC countries such as Russia chip in with a further 600,000 b/d. That would amount to almost 2% of global production, far more than markets expected. It showed that OPEC is not dead yet.
The size of the proposed cut, the first since 2008, caused a surge in Brent oil prices to above $50 a barrel. Some speculators think it may mark the beginning of the end of a two-year glut in the world’s oil markets, during which prices have fallen by half and producers such as Venezuela have come close to collapse. As long as prices continue to recover, Saudi Arabia can probably shrug off the fact that its previous strategy damaged OPEC at least as badly as non-members, and that this week’s deal gave more breathing space to its arch-rival Iran than it would have liked.
The rally’s continuation, however, depends on non-OPEC members such as Russia reliably committing…Continue reading
The dollar’s strength is a problem for the world

WHEN economic historians look back on the years following the global financial crisis, they might ponder the exact moment at which the boom in offshore dollar-lending reached its zenith. Was it September 2012, when Zambia issued its debut Eurobond (dollar-denominated bond), at a yield of 5.4%, and received $12bn of orders? Perhaps it was a year later, when investors gobbled up an $850m Eurobond issue by a state-backed tuna-fishing venture in Mozambique. In between Petrobras, Brazil’s state oil company, was able to issue $11bn of ten-year bonds in May 2013, a record for an emerging-market firm, at a generously low yield of 4.35%.
Investors had reason to regret those purchases even before the dollar’s latest surge. Between November 9th, when Donald Trump won the presidential election in America, and the Thanksgiving holiday, the dollar rose by 3% against a basket of rich-world currencies. Such a jump in so short a time is rare. The dollar-borrowing binge during these years helps explain why the greenback bounced so sharply.
By the end of last year, governments and businesses outside America had racked up $9.7trn of debts denominated in…Continue reading
What Donald Trump’s election means for government-bond markets

THE death of the long bull market in bonds has been called many times in recent years. Such a consummation is devoutly wished for by those who think the global economy will never get back to health until short- and long-term interest rates return to more normal levels.
Following the election of Donald Trump as American president, the funeral rites are being read again. The yield on the ten-year Treasury bond jumped from 1.73% (while the votes were being counted) to 2.36% at one stage; the yield on the two-year bond rose from 0.78% to 1.12%. (Bond prices fall as yields rise.)
The rationale for the shift is the belief that Mr Trump will push through a fiscal stimulus, in the form of tax cuts and infrastructure spending. Not only will that boost the American economy but it will allow the Federal Reserve to return monetary policy to more “normal” levels by pushing up rates from the current 0.5%. It could also lead to higher inflation in the medium term. Forecasts for American inflation in the early 2020s can be derived from the bond market. In July, they pointed to 1.4%; now they imply 2.1%. All three factors—faster…Continue reading
The dire consequences of India’s demonetisation initiative

SUPPOSE that one day the government of a large and fast-growing economy became convinced that its highest priority was to purge the country of black-economy millionaires hoarding piles of illicit cash. Seeking popular approval, it sent the printing presses into overdrive, hoping to inflate away the value of these secret piles of wealth. It worked: rising prices struck a blow against the undeserving rich, and by egging on others to deposit their money in banks (where it could at least earn interest), the shadow economy shrank. The government could plough the newly created money into tax breaks and public-works schemes.
Critics, rightly, would stand aghast. Inflation would affect everyone who held cash, law-abiding or not. Much of the wealth of those enriched by the black economy would be insulated, because lots of their lucre is held not in cash but in property, gold or jewellery. Such heavy-handed measures could undermine the credibility of important government institutions. Fear that they might be used again in future could weaken confidence in the currency as a store of value—paving the way for some broader institutional failure, like hyperinflation….Continue reading