
Tag: Business and finance
One bitcoin is worth twice as much as an ounce of gold
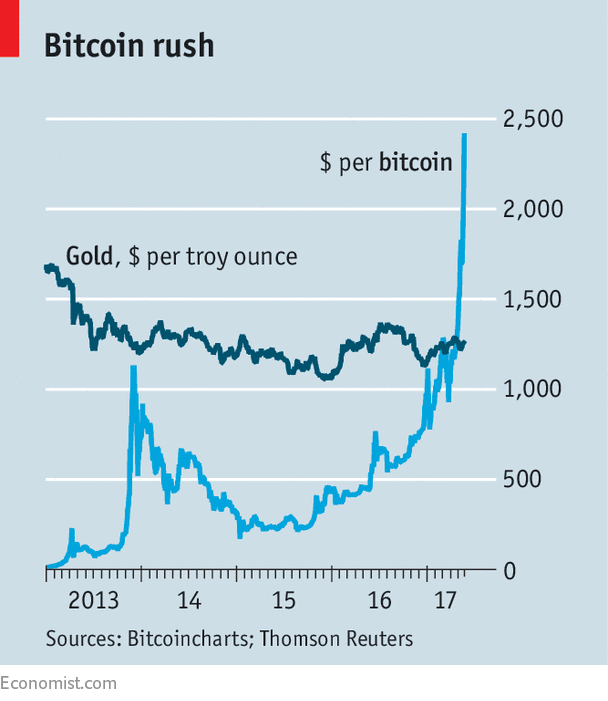
Fans of bitcoin, a crypto-currency, have long called it digital gold. Now this sounds like an insult: continuing its stellar rise, and adding more than 30% to its value in just a week, one bitcoin is worth more than $2,600, over twice as much as an ounce of gold. As The Economist went to press all bitcoins in circulation were worth over $43bn. A sum of $1,000 invested in bitcoins in 2010 would now be worth nearly $36m. Other crypto-currencies are also marching upward: together this week they were worth $87bn. But if the history of gold is any guide, what goes up will come down—and then go up again.
Is efficient-market theory becoming more efficient?
BUILD a better mousetrap, the saying goes, and the world will beat a path to your door. Find a way to beat the stockmarket and they will construct a high-speed railway. As investors try to achieve this goal, they draw on the work of academics. But in doing so, they are both changing the markets and the way academics understand them.
The idea that financial markets are “efficient” became widespread among academics in the 1960s and 1970s. The hypothesis stated that all information relevant to an asset’s value would instantly be reflected in the price; little point, therefore, in trading on the basis of such data. What would move the price would be future information (news) which, by definition, could not be known in advance. Share prices would follow a “random walk”. Indeed, a book called “A Random Walk Down Wall Street” became a bestseller.
The idea helped inspire the creation of index-trackers—funds that simply buy all the shares in a benchmark like the S&P…Continue reading
What the German economic model can teach Emmanuel Macron
IT IS heartening that the euro area has a knack for surviving near-fatal crises. Yet confidence in the durability of the single currency might be stronger if it suffered fewer of them. Europe dodged its latest bullet on May 7th in France, when Emmanuel Macron, a liberal-minded (by local standards) upstart centrist, defeated Marine Le Pen for the presidency. Even so, an avowed nationalist and Eurosceptic captured 34% of the vote, leaving Mr Macron with five years to assuage widespread frustration with the economic status quo. An obvious model lies just across the Rhine, where the unemployment rate—below 4%, down from over 11% in 2005—is testimony to the potential for swift, dramatic change. Yet Germany’s performance will not be easy to duplicate.
It would be unfair to call France the sick man of Europe; half the continent is wheezing or limping. Yet there is certainly room for French improvement. Real output per person has barely risen in the past decade. Government spending stands at 57% of GDP, outstripping the tax take; France’s budget deficit, at 3.4% of GDP, is among the largest in the euro area’s core. The biggest worry, however, is the labour market. The unemployment rate, now 10.1%, is stubbornly high. Nearly a quarter of French young adults are unemployed. Worklessness, especially among young people, is a source of rising social tension and a…Continue reading
An abrupt change at the top at Ford
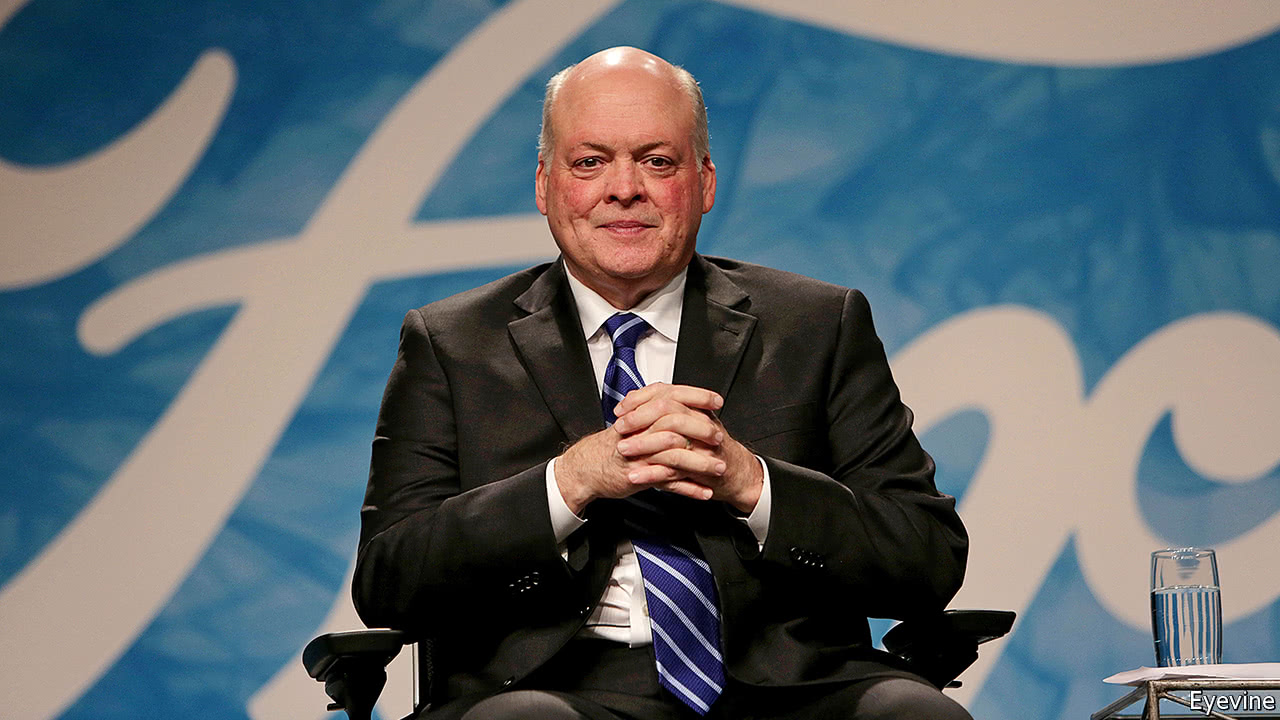
THE abrupt departure of Ford’s boss, Mark Fields, which the firm announced on May 22nd, has two explanations. Investors had become restive at its performance, particularly in the past year. But Mr Fields was also perceived to lack the drive of Alan Mulally, the man he succeeded. In replacing him with Jim Hackett (pictured), who ran an office-furniture company before joining Ford’s board in 2013 and more recently led the firm’s mobility unit, Ford hopes to conquer current problems and shore up its future strategy.
Ford’s shares have declined by nearly 40% since Mr Fields took over (see chart). Though it made record profits in 2015 and had strong results in 2016, investors reckoned a booming North American market, on which it relies for nearly two-thirds of revenues, would slow. They also disliked the fact that Mr Fields had to invest heavily in new technologies. Ford suffered the ignominy of its market capitalisation being…Continue reading
Among private tech firms, Airbnb has pursued a distinct strategy

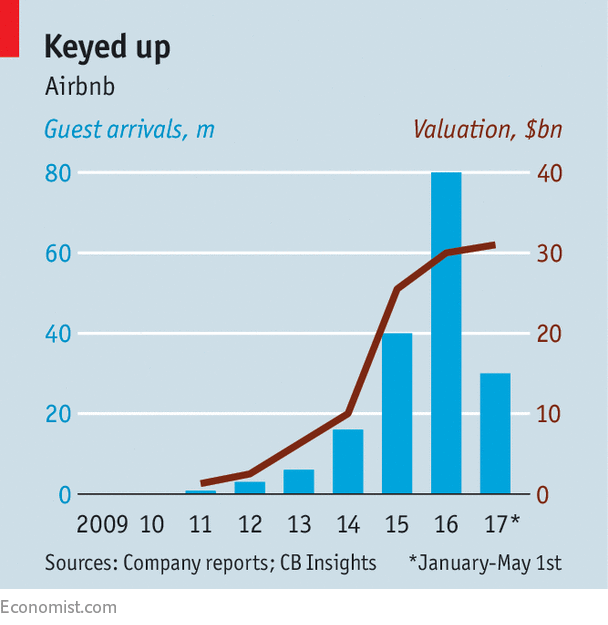
UNTIL recently “Uber envy” afflicted many top executives at Airbnb, a platform for booking overnight stays in other people’s homes. So admits a big investor in the firm. The two companies often raised money at the same time, and the ride-hailing giant reliably received more cash and closer attention. Uber is America’s most valuable private technology firm, with a valuation of close to $70bn at last count; Airbnb is still in second place with a value of around $30bn. But with Uber facing a series of setbacks, including allegations of intellectual-property theft, departures by senior executives and a consumer boycott, jealousy in Airbnb’s hallways has largely evaporated.
 Continue reading
Noble Group, a big Asian commodities trader, is teetering
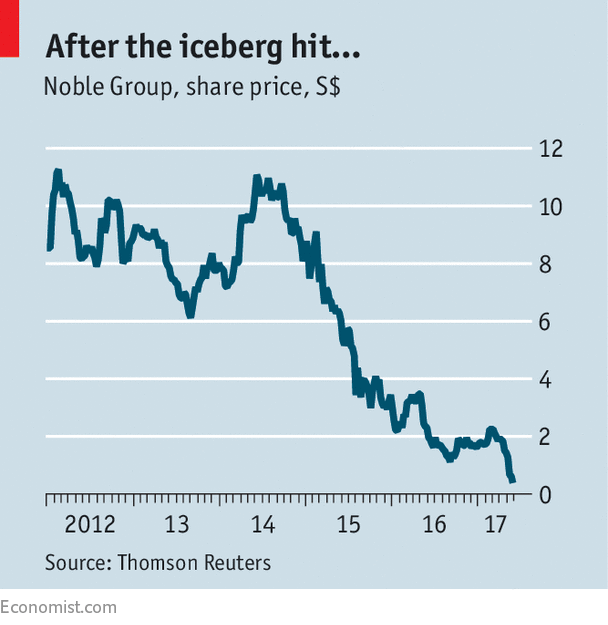
THE difficulties facing Noble Group, a beleaguered Hong Kong commodities trader, are multiplying. On May 23rd the firm was forced to suspend trading of its shares in Singapore after their value slumped by more than 28% in half an hour. The panicked selling came after S&P Global, a ratings agency, warned that Noble was at risk of defaulting on large debt repayments that are due within the next 12 months. Investors were also rattled by reports from Reuters and the Financial Times suggesting that Sinochem, a Chinese conglomerate at one time tipped to take a stake in Noble, had lost interest in a deal.
Founded in 1986 by Richard Elman, a former scrap-metal merchant from London, Noble grew from an initial investment of $100,000 to be worth more than $10bn at its peak in 2010. But investors took fright in 2015 when a previously unknown group called Iceberg Research began publishing reports questioning Noble’s accounting practices (Noble has vigorously defended its…Continue reading
To forecast share returns, count buy-backs as well as dividends
WHAT is the point of buying shares? Ultimately investors must hope that the cash they receive from the company will offer an attractive long-term return.
Over the long run, reinvested dividends rather than capital gains have comprised the vast bulk of returns. But since the 1980s American firms have increasingly used share buy-backs, which have tax advantages for some investors. Buy-backs have been higher than dividend payments in eight of the past ten years.
In a buy-back, investors receive cash for a proportion of their holdings. A new paper* in the Financial Analysts Journal argues that adding this to dividend receipts to calculate a total payout yield gives a better estimate of future returns than the dividend yield alone. It also reveals a much better match between stockmarket performance and overall economic growth.
Using data going back to 1871, the authors find that the average dividend yield has been 4.5% and the total payout yield 4.89%. Since 1970 the dividend yield has dropped to 3.03%, but the total payout yield has averaged 4.26%. Looked at on that basis, the overall income return from shares has been not that far below historical levels.
The return from shares can be broken down into three components: the initial income yield; growth in the income stream; and any change in valuation. (If shares become more…Continue reading
Donald Trump’s budget ignores what is ailing American workers

PRESIDENTIAL budget requests are worth exactly nothing. They carry no force of legislation. They land, heavy, bound and shrink-wrapped, so they can be immediately binned as Congress continues its now yearly stumble toward a “continuing resolution”—a supposedly temporary legislative act that in recent decades has almost entirely replaced the statutory budget process. The request from the President is the least consequential part of something that is completely broken. It functions like a bumper sticker on an old car. It only tells you about the person who’s driving.
Mick Mulvaney, a former congressman from South Carolina who won his seat in the Tea-Party wave of 2010, runs Donald Trump’s Office of Management and Budget. Mr Mulvaney has created the budget his wing of the Republican party always wanted: government as a service, paid for by its clients, the taxpayers. If you receive more than you pay, the system has failed, and must be fixed. The marketing copy that accompanied the budget calls this “respect for people…Continue reading
The strange tales of ministers and kings flying commercial jets

ONE of the more disquieting rumours of the year is that of the Iraqi transport minister who reportedly demanded a turn at the yoke of a plane carrying 200 passengers flying from Baghdad to Basra. According to a report in the New Arab last month, and a witness account on al-Sharqiya television news, the politician entered the cockpit and asked if he could land the plane. The captain told his co-pilot to give his seat to the minister so that he could land it under his supervision. New Arab quoted one official, speaking on the condition of anonymity: «The minister did not do a good job. He slammed the front of the plane into the ground, sending the passengers into a panic.»
That all sounds a bit far-fetched to Gulliver. (The Iraqi Civil…Continue reading
The “I’ve paid in all my life” fallacy

SOCIAL security is often described as the “third rail” of American politics—touch it and you die. Britain’s prime minister has just tied herself into a tangle over the way to fund long-term care for the elderly.
The problem is made more difficult because of the way that such benefit schemes were established and marketed to the public—as insurance schemes in which what you receive in benefits relates to what you put in. When pension schemes were set up by Franklin Roosevelt (pictured left) in the 1930s or in Britain, by David Lloyd George (pictured, right) in the Edwardian era, the insurance notion was something people could easily grasp (private schemes already existed) and could be seen as fair.
This was fine in the early years of such schemes when the number of people contributing was far greater than the number of people taking benefits. But as our societies age, the costs rise and the inadequacy of…Continue reading